Category: Insurance
The Hidden Investment Potential of Your HSA
October 1, 2026
Health Savings Accounts were introduced in 2004 as part of the Medicare Prescription Drug, Improvement, and Modernization Act during the George W. Bush administration. These accounts allow those with a High Deductible Health Plan (HDHP) to open a tax-free health savings account to help pay medical expenses until they meet the high deductible.
Unlike a Flexible Savings Account or FSA, if there is still money in your account at the end of the year, then you may roll those funds over into the next year – even if you no longer have an HDHP. Therefore, if you save $3000 in your HSA account and only spend $1200 on medical expenses, then the remaining $1800 will stay in your account the following year.
In addition to helping those with an HDHP pay for their medical expenses tax-free, an HSA can actually be a wise investment account when approached correctly.
Here’s everything you need to know about optimizing your HSA.
The Triple Tax Advantage
An HSA is a triple tax-free account, which means that the contributions you make are tax-deductible, your earnings grow tax-free, and as long as the funds are spent on health care, it comes out of the account tax-free, too.
“You get a tax benefit on the way in. You get a tax benefit when it’s growing, and you don’t pay any tax coming out,” says Jay McGowan, financial expert at The Welch Group.
Yet another perk of an HSA is that you do not have to take your funds out the same year you receive health care. As long as you save your receipts, you can withdraw that money much later. For instance, if you have a baby when you’re 35 and keep every out-of-pocket receipt, you could withdraw that HSA money at age 55 and use it to buy anything you want, free of any taxes or penalties.
Technically, you can spend your HSA funds on anything, but if you withdraw money for non-health care expenses before age 65, then you will have to pay taxes at your marginal tax rate on the entire withdrawal, as well as pay a 20% penalty. If you spend funds on anything besides health care after 65, you’ll still be taxed, but you won’t be penalized.
Contribution Limits
You can accept contributions from anyone, an employer, and yourself. For 2026, the maximum annual contribution limits are $4,400 for self-only coverage and $8,750 for family coverage.
“You have to be enrolled in a high deductible health care plan to be eligible to participate in an HSA,” says McGowan.
For 2026, a qualified HDHP has the following minimum and maximum yearly deductibles with other out-of-pocket expenses:
- Self-only coverage: $1,700-$8,500
- Family coverage: $3,400-$17,000
Even though your HSA has annual contribution limits, your total balance has no limit. That means that if you consistently make your maximum contributions without withdrawing funds, your balance can grow significantly over time.
Building a 6-Figure HSA
If you are fortunate enough not to have any major health care needs, then an HDHP might be the right choice for you. If you’re healthy, you may not even need to touch those HSA funds, allowing them to roll over each year.
If you can afford to max out your HSA at the beginning of the year, then your balance can start compounding tax-free as soon as possible. Then, if you can also pay the majority of your health costs without using your HSA, then you can save all of those receipts and withdraw the money tax-free later on, when you need it more.
Many people don’t realize you can invest the money in your HSA. Most HSA providers pay less than 0.5% interest a year. But they also let account holders move funds from the cash portion to mutual funds, exchange-traded funds, or other investment options they offer.
By making maximum contributions, saving your HSA funds for later, and investing part of your balance, you could grow a six-figure healthcare reserve.
Spending on Health Expenses
The best thing to do with your HSA, of course, is to use it on what it’s meant for: to pay for your health care. According to Fidelity Investments, a 65-year-old who retires in 2026 may spend an average of $185,500 on health and medical expenses during retirement, up 7.5% from last year. If your health care expenses are low now, they may not always stay that way.
“The best place to start is to look at your regular health care expenses, like if you go to the dentist twice a year, if you get glasses, if you know you go to your doctor or have prescriptions,” says Carolyn McClanahan, a physician and founder of Life Planning Partners.
Once you have a realistic estimate of your annual health care expenses, then you can start optimizing your HSA spending.
Your funds can be used tax-free for qualified medical expenses, which generally include:
- Doctor and hospital visits
- Prescriptions
- Over-the-counter medications and health care products
- Dental care
- Vision coverage
- Mental health services
- Medical equipment and supplies
“If you’re on a high deductible plan with an HSA, then you should max out your HSA every year, irrespective of your health-care costs or your deductible,” says McClanahan. “One, you get a great tax savings, and two, you get to use that tax-free for any health-care expense the rest of your life. So you want to build that account up.”
Don’t Leave Behind an HSA
The worst kind of account to inherit is an HSA. It becomes 100% taxable to the heir at ordinary income tax rates the year you pass away. But if you donate the money to a charity, it remains tax-free. If you want to leave something behind for anyone, an IRA or a life insurance policy may be a better option. Experts recommend spending your entire HSA balance before passing and leaving the remainder to your heirs.
At Insureyouknow.org, you can store all your financial and medical records in one organized place, making it simple to plan for the future and optimize your HSA investment options.
Top 3 Vital Documents Every Senior Needs to Organize Today
April 1, 2026
Every single year, thousands of older homeowners throw away hundreds, even thousands, of dollars. Why? They simply didn’t file the right piece of paper. Meanwhile, families are out there making agonizing medical choices in crowded hospital hallways because nobody knows where mom or dad put their living will. And don’t even get started on Medicare benefits lost to the void of a messy filing cabinet.
These aren’t freak accidents. This stuff happens constantly to otherwise prepared families who just didn’t get their paperwork sorted in time.
If you’re a senior, or helping one manage their affairs, three specific types of documents need your attention right now: property tax exemptions, Medicare files, and advance directives. Getting a handle on these and actually keeping them where people can find them protects your money, honors your medical choices, and cuts out the panic when things go sideways.
Why Property Tax Exemption Documents Are More Important Than Ever
Sure, most older homeowners know property tax breaks exist. But hardly anyone realizes exactly how much cash they’re leaving on the table by not claiming them or by forgetting to renew them.
Fast forward to 2026, and a bunch of states have seriously beefed up their senior tax relief. Take New York: qualifying homeowners 65 and up can now shield up to 65% of their home’s assessed value from taxes (up from the old 50% cap). In New Jersey, the Stay NJ program is knocking up to $6,500 a year off tax bills for households making under $500,000. Over in Texas, they’ve expanded the over-65 school district exemption so much that plenty of folks aren’t paying school taxes at all anymore.
Here’s the catch, though. They don’t just hand this money to you automatically. In Texas alone, roughly 15% of eligible folks never file for their homestead exemption. That’s about $1,500 a year just evaporating. You see the same thing happening nationwide.
And then there’s the renewal trap. A lot of these tax breaks force you to refile every single year. Miss a random deadline in March or April? You lose the discount for the whole year. If your proof of age, income, and residency isn’t sitting somewhere obvious, blowing past that deadline is incredibly easy.
Here is what you actually need to keep handy:
- Proof of age (like a birth certificate or government ID)
- Proof you actually live there (mortgage statements, recent utility bills)
- Your latest income info (Social Security award letters, tax returns)
- The actual exemption application and those annoying annual renewal notices
- Any random letters the county assessor mails you
When you finally get this stuff organized ideally in a secure digital spot that your kids or trusted contacts can reach claiming your tax break turns into a quick annual chore instead of a frantic scavenger hunt.
The Medicare Documents That Too Many Families Cannot Find
Medicare is arguably the most crucial benefit you’ll ever get. Yet, the paperwork usually ends up shoved in a jammed desk drawer nobody else can open. Or worse, sitting in a messy pile on the kitchen counter.
For seniors and the people taking care of them, there’s a core stack of Medicare records you absolutely must keep safe and share with at least one person you trust.
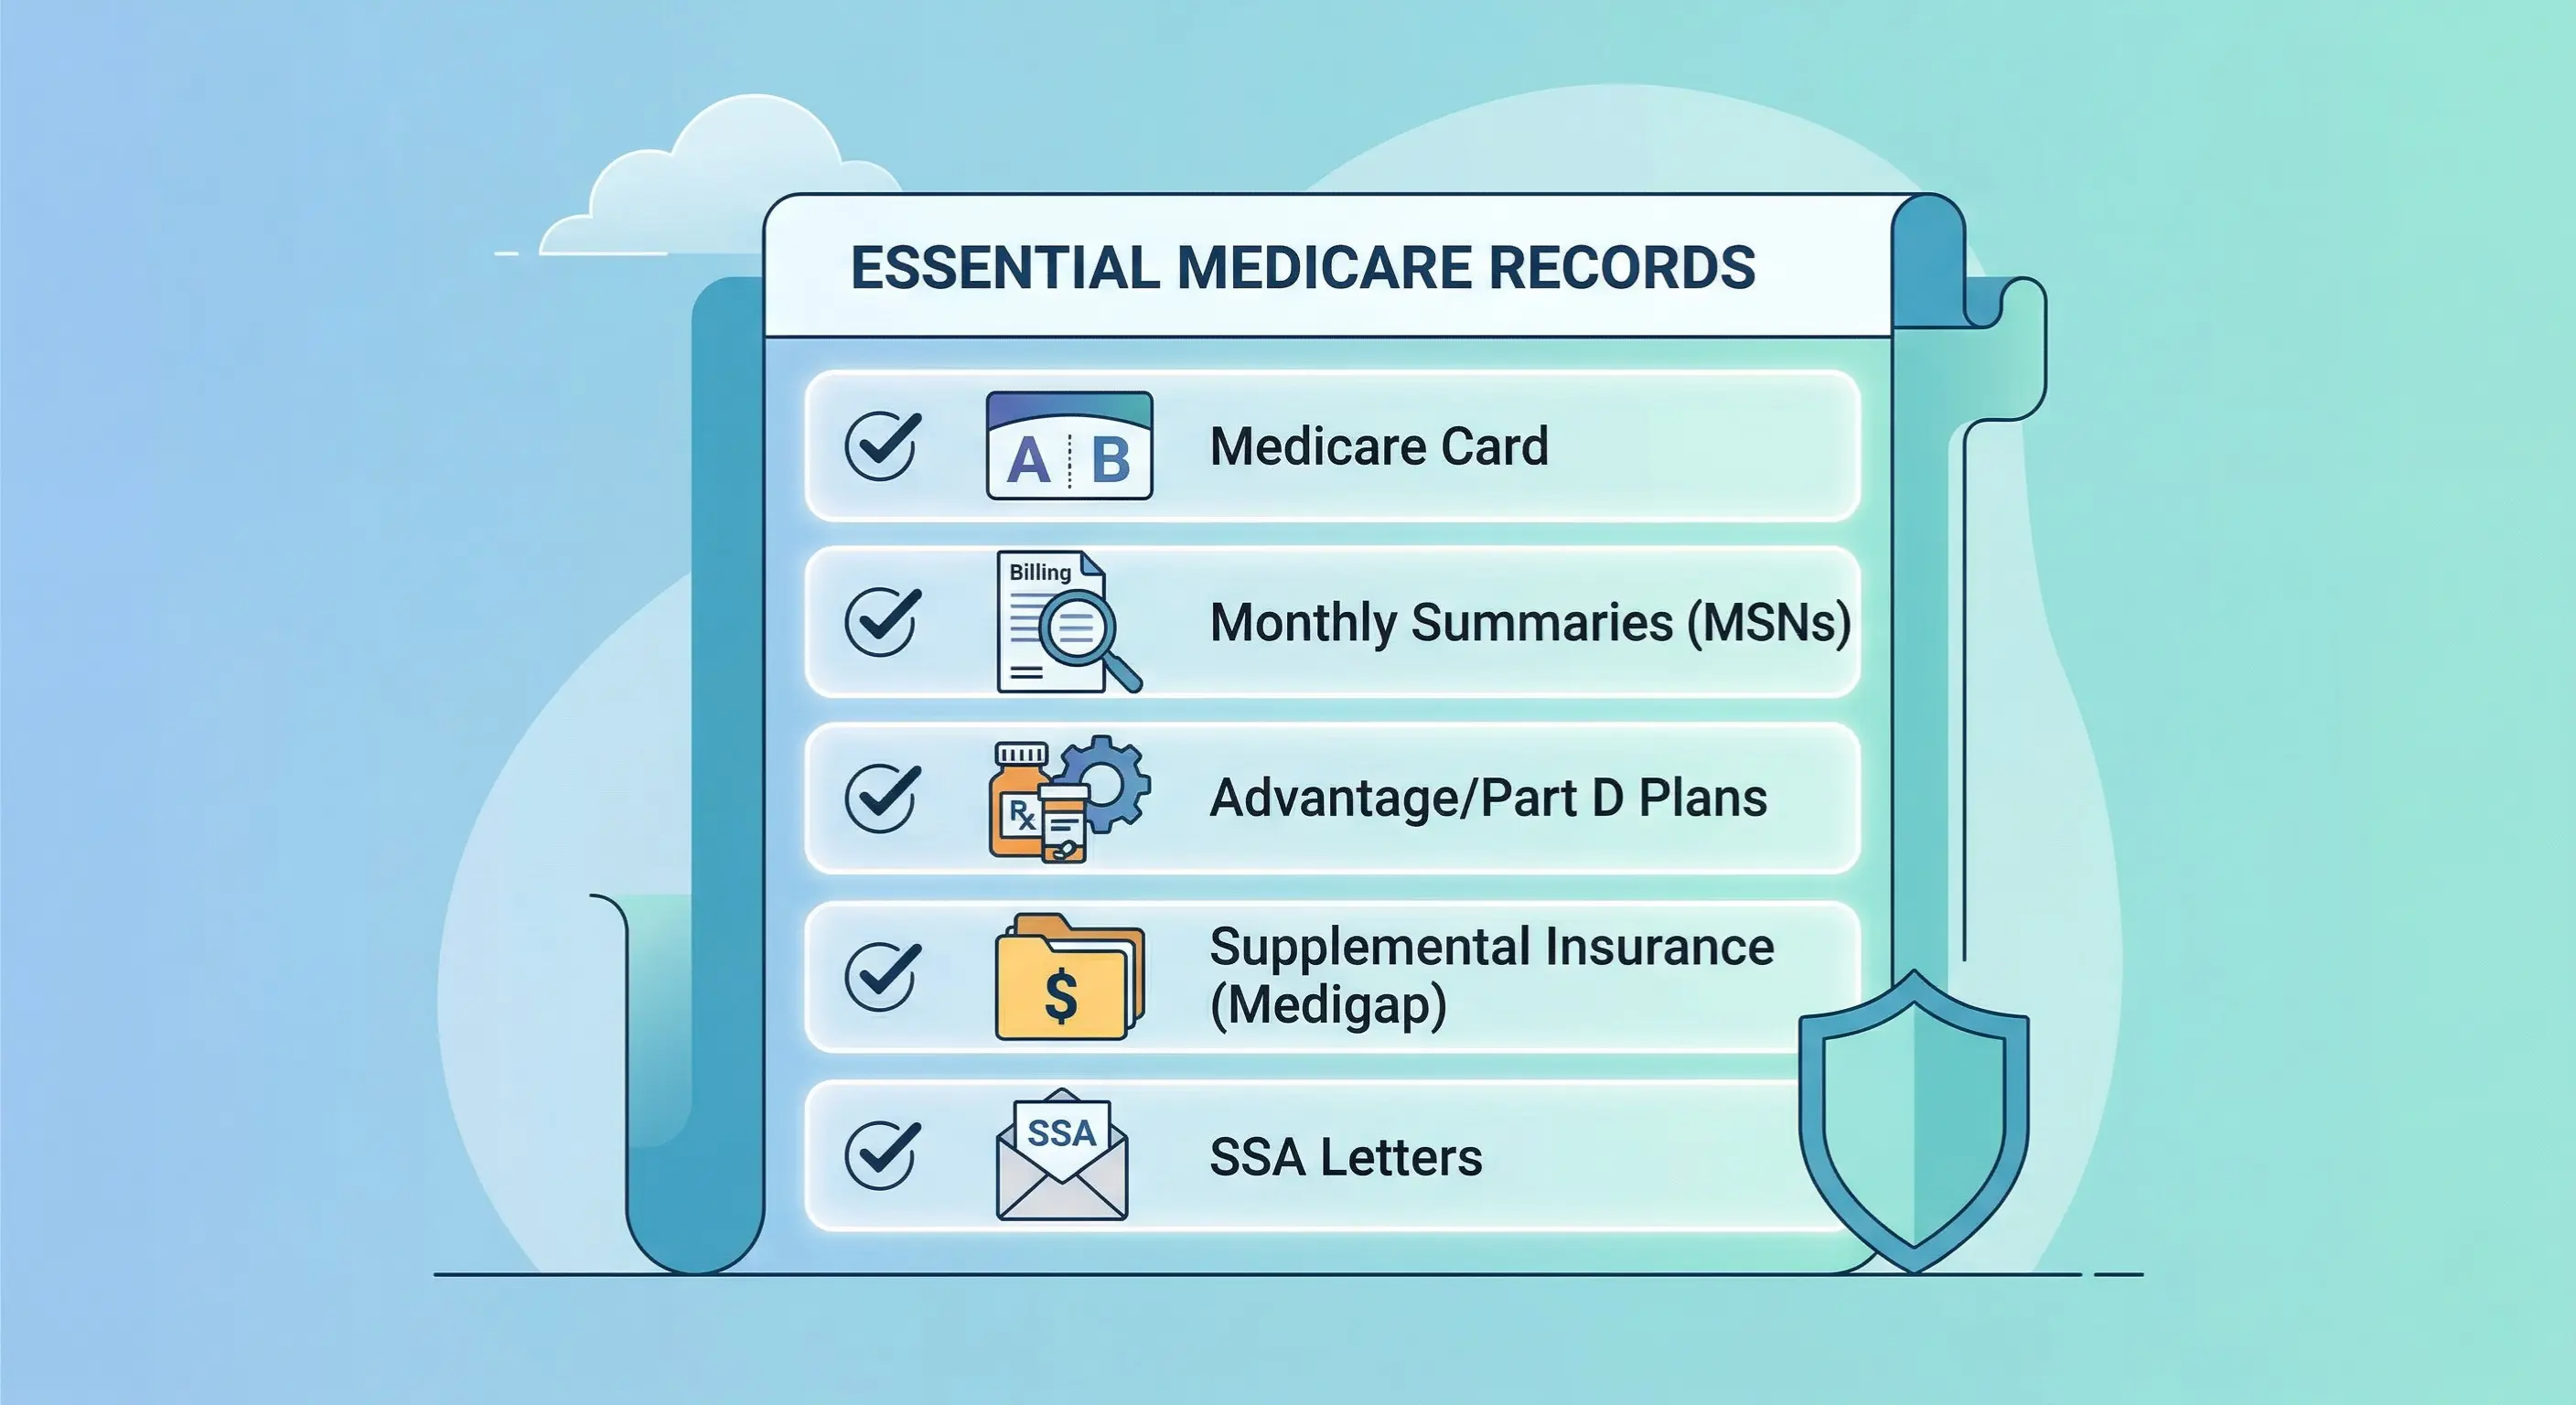
Keep these essential Medicare records organized:
- Your actual Medicare card (Part A and Part B)
- Medicare Summary Notices (MSNs) these are the monthly statements showing what they billed and what Medicare actually covered
- Enrollment docs for your Medicare Advantage or Part D plan
- Explanation of Benefits (EOB) from any Medigap or supplemental policies
- Letters from Social Security about your eligibility or premiums
- Paperwork for the Medicare Savings Program, if you use it
- Any records of fights or appeals with Medicare
Look, this isn’t just busywork. These papers prove you have coverage during an emergency. They help you spot billing fraud. They are totally necessary when you’re trying to coordinate care between three different doctors. If you end up in the hospital and your daughter needs to argue with the billing department, handing her these records will save her hours on hold and prevent massive bills.
Also, remember that Medicare Part B pays for a voluntary chat with your doctor about advance care planning. If you do this during your annual wellness visit, it shouldn’t cost you a dime out of pocket. Keep the notes from that conversation on file, too.
Living Wills and Advance Directives: The Documents That Speak When a Senior Cannot
Out of everything you could possibly organize, the living will is probably the most personal. It’s also the one document guaranteed to go missing right when everyone desperately needs it.
The University of Michigan’s National Poll on Healthy Aging found something pretty alarming: 54% of adults between 50 and 80 haven’t bothered with an advance directive or living will. So what happens? A medical crisis hits, and total strangers (doctors who just met the patient) or terrified family members have to make gut-wrenching decisions under crazy pressure.
A living will is just a legal paper that outlines what medical treatments you want if you can’t speak for yourself. A healthcare proxy (sometimes called a durable power of attorney for healthcare) officially names the person you trust to make those choices for you. The living will itself gets into the weeds about things like dialysis, ventilators, resuscitation, and feeding tubes.
And please don’t think this is only for the very old or the terminally ill. Car accidents and strokes don’t check your calendar. It is so much better to write a living will at 65 while you’re healthy than to try scraping one together at 85 in the ICU.
Make sure you store and share these key advance directive documents:
- The living will itself
- Durable power of attorney for healthcare
- Your POLST or MOLST form (Physician Orders for Life-Sustaining Treatment), if you have one
- The actual healthcare proxy paperwork
- Your written wishes regarding organ donation
- Copies of all this given to your primary doctor and any major specialists
Quick tip: if you’re a snowbird splitting time between two states, do yourself a favor and create an advance directive for both. Keep copies of both documents together in both houses.
The Common Thread: These Documents Are Useless If No One Can Find Them
A tax exemption that lapsed. A Medicare card buried in a shoebox under the bed. A living will locked tight in a safe that only grandpa knew the combination to. This exact nightmare plays out in living rooms across the country every single day.
The real goal here isn’t just printing out forms. It’s about locking them down somewhere secure, actually keeping them up to date, and making sure your trusted point person knows exactly where to look when the time comes.
That is exactly why platforms like InsureYouKnow.org exist. It’s a secure, encrypted digital safe deposit box. You can stash your vital records there, give access to the people you trust, and even set up nudges to review everything once in a while. Nobody wants to do paperwork just for fun. You do it for the peace of mind.
You do it so that when life throws a curveball, the right papers are in the right hands immediately.
Seniors and their families already have enough stress to deal with. Getting your records straight today basically guarantees you one less crisis tomorrow.
InsureYouKnow.org is a secure electronic safe deposit box for life’s most important information. The platform does not provide legal, financial, or insurance advice it helps ensure that the right people have access to the right documents when they need them most.
How to Tell Your Beneficiaries About Life Insurance Without Stress
March 19, 2026
Billions of dollars in life insurance death benefits sit unclaimed across the United States annually. Families often desperately need these funds, and the policies themselves remain completely valid. The problem usually stems from a simple communication gap where the named individuals had no idea the coverage even existed.
Industry investigations revealed major insurers releasing over $7 billion in previously forgotten benefits between 2006 and 2016, but only after regulators forced them to cross-reference death records. Experts strongly believe the actual amount of missing money is substantially higher. Current data points to roughly $6 billion in unpaid benefits sitting in limbo, largely caused by outdated contact details and uninformed relatives.
This situation is entirely preventable. Fixing the issue does not demand expensive attorneys, formal family meetings, or highly uncomfortable discussions. Policyholders just need to share the right details clearly and proactively so the information actually sticks.
Why Beneficiaries Remain in the Dark
Policyholders avoid talking about their coverage for several reasons. Some individuals harbor superstitions regarding death. Others fear the topic might sound morbid or cause unnecessary distress among relatives. A large portion of people simply assume loved ones will figure everything out when the moment arrives.
Insurance providers lack automatic alert systems to notify anyone when a policyholder passes away. No alarm sounds and no automatic check gets mailed. Companies usually only discover a death has occurred when a relative reaches out directly. That requires the family to actually know about the coverage beforehand.
The most frequently forgotten accounts include decades-old plans, employer-sponsored group coverage from previous jobs, and small whole-life policies intended for final expenses. Important paperwork easily gets lost during house moves. Premium drafts might quietly exit a bank account for years without a surviving spouse noticing. Lacking a clear handover of documents leaves surviving relatives guessing and frequently finding nothing.
Starting the Conversation Without Uncomfortable Feelings
Discussing these financial safeguards never has to sound like a grim announcement. Financial planners frequently suggest centering the talk on care and future preparation instead of loss. A simple mindset shift changes everything. The focus moves away from passing away and toward actively protecting important family members.
Several approaches help these talks feel completely natural:
- Tie it to a life event: Welcoming a new grandchild, navigating a health scare, or updating a will provides an easy opening. Someone might say, “While getting these organizational tasks done, it is important to share the details of this life insurance coverage.”
- Frame it as a gift: Informing dependents about their financial protection acts as a generous gesture. Policyholders can position the talk as offering clarity. A good phrase to use is, “To prevent any future scrambling, here are the essential details needed for the records.”
- Use a document review as the opener: Checking financial records every year builds excellent habits. Inviting an adult child or spouse to observe the review creates a low-pressure environment to share policy specifics naturally.
Essential Information for Beneficiaries to Know
Mentioning the mere existence of a policy falls short of being helpful. Grieving relatives require highly specific data to process claims quickly. Handing over this data early minimizes delays, lowers stress levels, and guarantees the funds reach the intended destinations promptly.
The National Association of Insurance Commissioners recommends granting access to the following specific details:
- The exact name of the provider and the full name of the insured person as listed on the contract
- The specific policy number and the exact type of coverage selected
- The total death benefit value alongside any attached riders
- Direct contact details for the provider or the managing agent
- The exact physical or digital location of the official documents
- Clear distinctions between primary and contingent individuals along with the designated percentage splits
Any individual holding multiple plans through an employer, private company, or professional group must document and share every single one. Relatives frequently uncover hidden coverage months or years after a funeral, making thorough documentation crucial.
Explaining Primary and Contingent Beneficiaries Clearly
The difference between primary and contingent designations frequently causes confusion. A primary designation puts a person or entity first in line for the funds. A contingent designation acts as a backup, stepping up only if the primary individual cannot collect the funds due to passing away themselves.
Everyone named on the contract must understand their exact role. Splitting funds requires each party to know their specific percentage share. Transparent communication stops arguments and blocks potential legal headaches later on. It helps to remind everyone that designated beneficiaries on a contract will overrule any instructions written into a standard estate plan.
Keeping Documents Accessible During Critical Moments
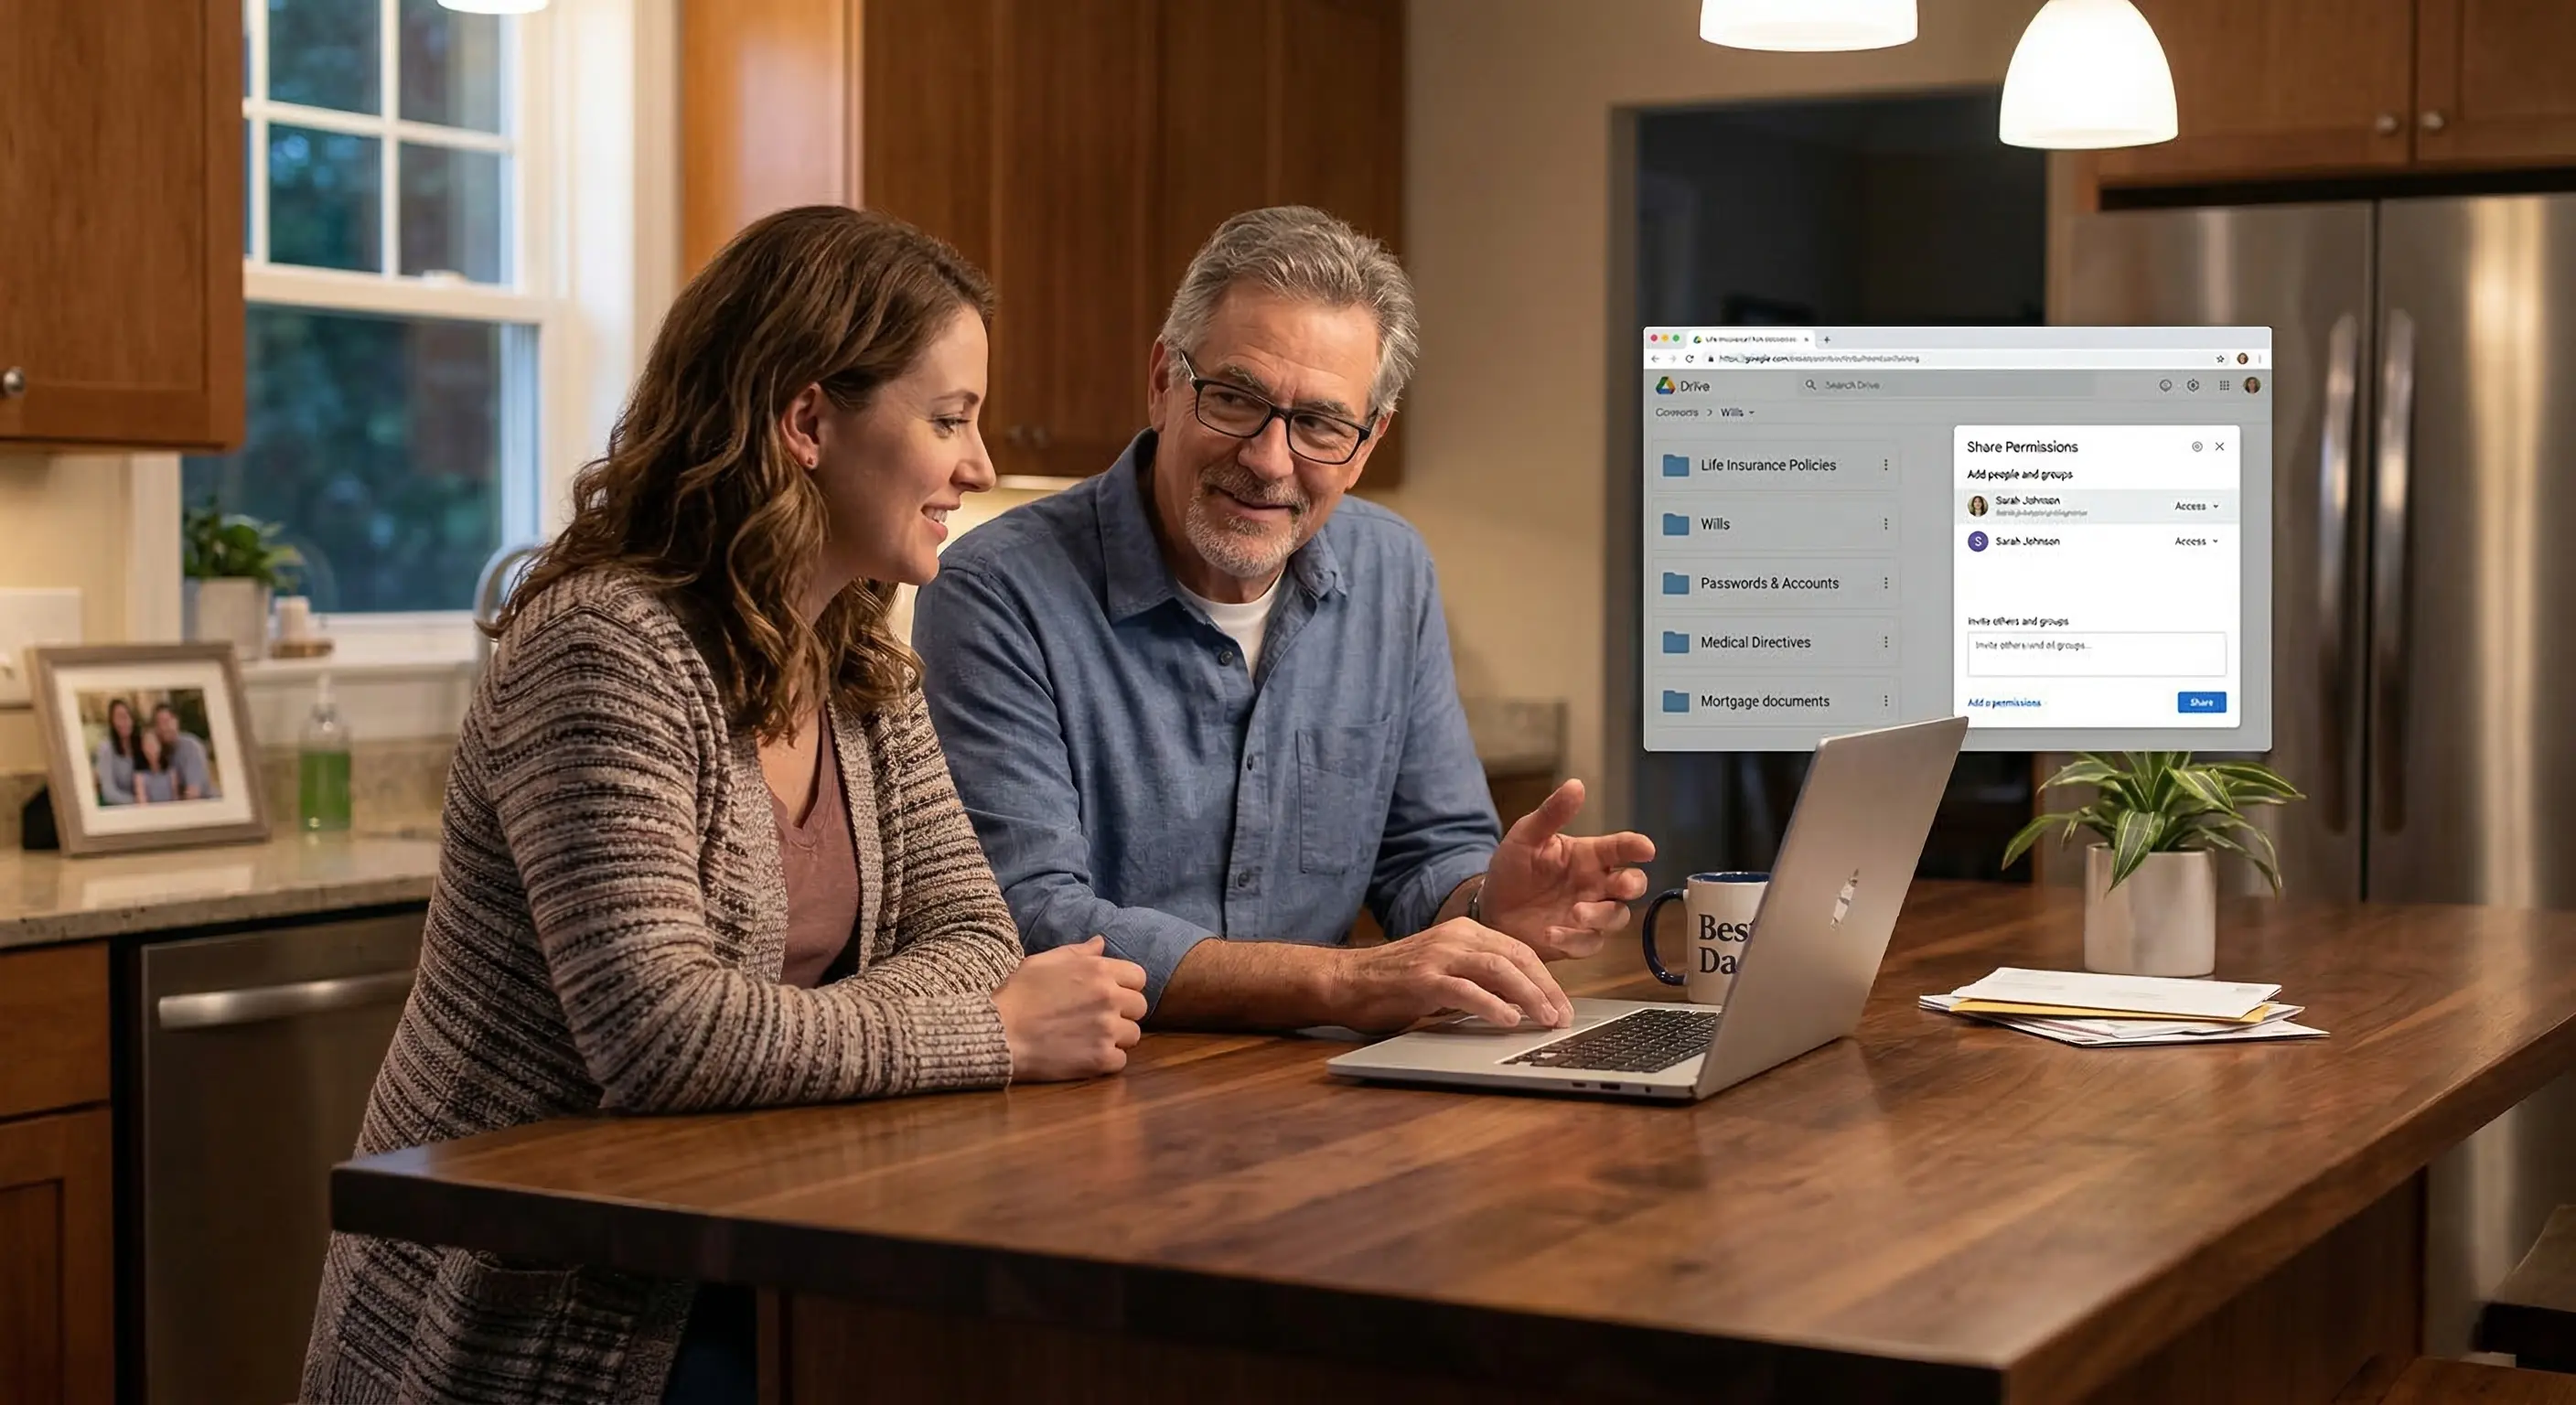
Spoken words offer a solid starting point but fall short long-term. People forget things quickly while grieving. Physical papers easily succumb to fires, floods, or misplacement during a move. The safest strategy pairs direct communication with a highly secure, centralized storage spot for all vital records.
Tucking the contract next to estate papers represents the traditional route, yet it carries flaws. Locking physical copies inside a bank safe deposit box often requires the policyholder to be present for access. This creates massive roadblocks for relatives at the worst possible time.
Digital platforms solve this accessibility problem beautifully. Encrypted online vaults allow users to stash life insurance details, medical coverage, banking numbers, and legal files in a single hub. Trusted contacts receive access to designated files, guaranteeing the correct people find the right information instantly from any location.
Updating Beneficiary Designations and Communicating Changes
Designations must evolve alongside major life shifts. Marriages, divorces, new babies, or the loss of a designated relative demand an immediate contract review. Neglected updates stand out as a top reason for delayed payouts and legal disputes. Industry research shows roughly 8% of claims hit roadblocks specifically due to obsolete contact data.
Updating a file means everyone involved needs a notification. Swapping out a former spouse for a new partner means both sides require an update, when appropriate. These chats might feel slightly awkward, but leaving a grieving family to fight over uncertain terms causes much deeper pain.
Creating an annual calendar alert to verify these designations builds a highly effective habit. Digital platforms often send automated monthly nudges to check for necessary updates. This turns file maintenance into a seamless part of standard financial upkeep.
Early Conversations Protect Loved Ones Tomorrow
Sharing policy details ranks among the most impactful financial steps a person can take. The process requires zero legal background and avoids feeling overly morbid. It just takes a willingness to speak directly and the discipline to organize the supporting paperwork.
Relatives who understand the coverage, know the storage location, and possess the correct contact numbers can actually focus on healing instead of hunting down forms. Providing that exact peace of mind remains the core purpose of buying coverage. The product only works if the protected individuals know it exists.
Utilizing an encrypted digital vault to hold these financial and legal records proves incredibly practical. This ensures the preparation goes far beyond spoken words. It builds an adaptable record that follows a family through every life stage, waiting quietly until the exact moment it becomes necessary.
Passkeys vs. Passwords: Why It’s Time to Switch Now
February 26, 2026
We all do it. Every morning. You grab your coffee, sit down, and try to log into your bank. Or maybe your insurance portal. You type in a password. Maybe it’s a strong one. Maybe it’s… well, let’s be real. It’s probably the same one you use for Netflix. But here is the hard truth: relying on a secret code just doesn’t cut it anymore. Not when your entire financial life is sitting behind it. Fast forward to 2026, and there is finally a better option that people are actually using: the passkey.
If you are the one stuck managing the heavy stuff for your family – wills, health records, the “in case of emergency” file – knowing the difference between a passkey and a password isn’t just tech trivia. It is a survival skill. It’s about keeping the wolves at the door away from the things that actually matter.
This guide breaks down exactly what passkeys are, how they smash the old-school password system, and why making the switch is probably the smartest move you can make right now.
What Is a Password – And Why Is It No Longer Enough?
Think about it. A password is just a string of letters you made up. It’s a secret handshake between you and a computer. And for a long time? That was fine.
But here is the snag: humans are involved. And humans? We are messy. The stats are pretty rough – something like 70% of hacks start because of a weak or stolen login. We reuse passwords because we’re lazy. We pick easy ones because we’re forgetful. Or we get tricked by a fake email and hand them over on a silver platter.
Common password headaches include:
- Brute-force attacks: Hackers have computers that can guess billions of passwords a second. If yours is simple, it’s gone before you can blink.
- The Dark Web: If one random site you use gets breached, your password ends up for sale. Suddenly, the bad guys have the keys to your whole life.
- Phishing: It is terrifyingly easy to get fooled by a fake email or website that looks real. You type it in, and poof – they have it.
- Fatigue: You have dozens of accounts. Remembering unique codes for all of them? Impossible. So we reuse them. And that is dangerous.
- SMS flaws: Even those text message codes aren’t bulletproof. Hackers can swap SIM cards and steal those codes right out of the air.
There is a saying in the security world that haunts me: Hackers don’t break in – they log in. If they have your password, they are you.
What Is a Passkey – And How Does It Work?
Passkeys are a total rewrite of the rules. Forget typing. A passkey uses public-key cryptography. Imagine a digital key that is split in two. One half sits on the website. The other half stays locked inside your phone or laptop.
When you want to log in, your phone and the website have a quick, silent chat. You prove it’s you by just unlocking your screen – Face ID, fingerprint, whatever. You don’t type a single letter. Nothing gets sent over the internet for a hacker to steal.
Think of it like a puzzle. The website has a piece. Your phone has a piece. They only fit together when you – the real you – are holding the device.
Key facts about passkeys:
- They run on the FIDO2 standard. Basically, the big tech companies all agreed on a better way to do things.
- Everyone is jumping on board: Google, Apple, Amazon, Chase Bank. They all support it.
- Millions of people are already using them without even realizing it.
- You can’t phish them. You can’t guess them.
- If you have a smartphone from the last few years, you are already ready to go.
Passkeys vs. Passwords: A Side-by-Side Comparison
Why is everyone making such a big deal about this? You have to look at the differences side-by-side to really get it.
1. Security
- Passwords: Weak. They can be stolen, guessed, or fished out of you with a fake email.
- Passkeys: Rock solid. The private key never leaves your phone. Even if a hacker breaks into the bank’s server, they can’t steal your key because it isn’t there.
2. Ease of Use
- Passwords: A pain. You forget them. You reset them. You type them wrong.
- Passkeys: Easy. You look at your phone, or touch the sensor. Done. It works 98% of the time and it’s way faster.
3. Phishing Resistance
- Passwords: Terrible. If a fake site looks real, you’ll probably type your password in.
- Passkeys: Perfect. A passkey is tied to the real website. If you land on a fake site, your phone knows. It simply won’t let you log in.
4. Device Dependency and Flexibility
- Passwords: You can use them anywhere, but that’s also why they are risky.
- Passkeys: They live on your device. But don’t worry – Apple and Google sync them to the cloud. So your passkeys are on your phone, your tablet, and your laptop automatically.
5. Risk in a Data Breach
- Passwords: If a company gets hacked, your password is leaked.
- Passkeys: If a company gets hacked, the hackers get… nothing useful. They just get a public key that can’t unlock anything without your phone.
Why This Matters for Protecting Vital Life Records
We usually don’t think about this stuff until it’s too late. You get hacked, or a family member passes away and nobody can get into their accounts. That is a nightmare scenario.
The accounts that hold your life’s work – insurance, savings, wills – need better protection than “123456.” If these get breached, it’s not just annoying. It’s identity theft. It’s losing money.
The banks know this. That’s why Chase and Wells Fargo are pushing passkeys. They want you safe.
If you are using a digital vault to keep your family’s info organized, turning on passkeys is the single best thing you can do today.
How to Set Up a Passkey (It Is Simpler Than It Sounds)
You don’t need to be a tech wizard. It takes two minutes.
Step 1: Go to your account settings (Google, Amazon, whatever).
Step 2: Look for “Passkeys” or “Security.”
Step 3: Click “Create Passkey.” Your phone will ask for your face or fingerprint. Do it.
Step 4: You’re done. Next time, just click “Use Passkey.”
Step 5: If you want to be extra safe, use a password manager like 1Password to keep them all organized.
Expert Tip: Start with the big ones. Email. Bank. Insurance. Get those locked down first.
Should Passwords Be Abandoned Entirely?
Not yet. We’re in a transition phase. Lots of old websites still need passwords. So here is the game plan:
- Switch to passkeys for anything important.
- Use a password manager to generate crazy long passwords for the junk sites that don’t support passkeys yet.
- Stop using SMS codes if you can help it. Use an app instead.
- Get a hardware key (like a YubiKey) if you are really paranoid about your email security.
- Check back often. More sites are adding this every month.
Microsoft went passkey-first last year and it’s been huge. By the end of 2026, typing passwords will feel like using a flip phone.
What Happens If a Device Is Lost?
Everyone asks this. “If I lose my phone, am I locked out forever?”
No. You’re fine.
- Cloud Sync: If you use an iPhone, your keys are in iCloud. Get a new phone, sign in, and they are back. Same for Android.
- Backup: You can still use other ways to get into your account if you absolutely have to.
- Thieves can’t use them: Even if someone steals your phone, they don’t have your face or fingerprint. They can’t use your passkeys.
Passkeys and the Future of Secure Document Storage
For families storing wills and financial docs online, security is everything. A digital vault is pointless if the key is under the mat.
Passkeys fix the human error part. You can’t accidentally give away your passkey. It solves the biggest problem in security: us.
Experts at Gartner and big tech firms are calling this the biggest shift in security in decades. The password era is ending. Finally.
Key Takeaways
- Passwords are weak. They are too easy to steal or guess.
- Passkeys are strong. They use heavy-duty encryption and your own biometrics.
- It’s happening now. Major banks and tech giants are already using them.
- Mix it up. Use passkeys where you can, strong passwords where you must.
- Don’t worry about lost phones. Cloud sync has your back.
- Protect your legacy. If you store vital records, this is a must-have upgrade.
Conclusion: The Lock Is Getting an Upgrade
Switching to passkeys isn’t just about cool new tech. It’s about peace of mind. Passwords put all the pressure on you to be perfect. Passkeys let your device handle the security so you don’t have to.
If you are serious about keeping your family’s future safe, stop waiting. Passkeys are here. They work. And they are way better than what you’re using now.
The best time to switch was yesterday. The second best time is today.
Protect What Matters Most
InsureYouKnow.org provides a secure, encrypted electronic safe deposit box for life’s most important information – insurance policies, financial records, healthcare documents, and more. Storing vital records in one organized, protected location means families are never left searching when they need information most. Start protecting what matters today at InsureYouKnow.org.
Medical History Cheat Sheet: What ER Doctors Need
February 4, 2026
The “Golden Hour” Gap
The Emergency Room is a storm. Noise. Chaos. Speed. Doctors and nurses fight the clock. They chase the “Golden Hour.” That tiny window where fast action beats death.
But silence is the enemy. Ambulances dump patients who can’t talk. Shock takes over. Or they are out cold. In that high-pressure moment, a missing detail, a drug allergy, an old surgery, sends the team down the wrong road. That road ends badly.
Ask any ER staffer. They agree on one thing. A simple “cheat sheet” is the best tool a person can bring through those doors.
Why Memory Fails in a Crisis
People think they will remember. “I know my meds,” they say. They are wrong. Trauma wipes the brain clean. Pain and fear take over. A patient knows they take a “heart pill.” The name? Gone. The dose? Forgotten.
A written paper fixes this. It talks when the mouth cannot. It stops the guessing game between a frantic arrival and safe care.
The ER Doctor’s Wish List: 6 Essentials
What goes on the paper? Forget the thick file. Medical teams want facts. Facts that change the plan right now.
1. The “Big Picture” Demographics
Before the IV goes in, the team must know who they are treating. They need to know who signs the forms.
- Full Legal Name and Date of Birth: This finds old records in the computer.
- Blood Type: Vital for fast transfusions.
- Emergency Contacts: A spouse. A parent. Someone who answers “yes” or “no” to surgery when the patient can’t.
2. The Medication List (Crucial)
This part kills people if it’s wrong. Drug interactions cause huge messes in hospitals. Be exact:
- Prescription Drugs: The name. The dose (like 50mg). The schedule.
- Over-the-Counter (OTC) Meds: Aspirin. Ibuprofen. They seem safe. They aren’t. They thin blood. They hit kidneys.
- Supplements and Vitamins: Herbal pills often fight with anesthesia.
Note: Never write “Take as directed.” That tells the doctor zero.
3. The Allergy Alert
Does the patient hate penicillin? Latex? Contrast dye? The team needs to know. Now. The wrong drug turns a broken bone into a breathing emergency. List the allergen and the reaction. “Penicillin: Hives.” “Peanuts: Throat shuts.”
4. Past Medical History (PMH)
Context is king. A stomach ache in a healthy teen is one thing. In a Crohn’s patient, it’s another.
- Chronic Conditions: Diabetes. Asthma. Epilepsy. High blood pressure. Heart issues.
- Implants: Pacemakers. Metal rods. Artificial joints. The team must know this before an MRI scan starts.
- Past Surgeries: A quick list. “Appendectomy, 2015.” “C-Section, 2020.”
5. Recent History
Sometimes the clue is new. A note about travel, especially overseas, helps. So does a note about recent hospital stays. This helps doctors spot weird infections.
6. Insurance and Directives
Life comes first. But paperwork causes headaches later. List Insurance Policy and Group Numbers. Also, check for an Advance Directive or DNR (Do Not Resuscitate) order. A copy must exist. Otherwise, the patient’s wishes get ignored.
Paper vs. Digital: The Accessibility Problem
Old advice? Keep a card in a wallet. But paper sucks. It fades. It tears. It gets lost. Or it sits in a kitchen drawer while the car crash happens three towns over.
Digital vaults like InsureYouKnow.org changed the game. Storing this “Cheat Sheet” in a secure cloud keeps data safe. It stays ready. A trusted partner pulls up the vault on a phone. Seconds later, the ER team has the facts.
The Final Diagnosis
Being ready isn’t paranoia. It is smart. A Medical History Cheat Sheet takes ten minutes. It pays off in safety. It lets doctors work faster. It stops bad errors. And it gives families peace. They know the health story is clear. Even when the room is silent.
Sandwich Generation Guide: Organize Parents’ & Kids’ Records
January 8, 2026
The Squeeze is Real
The term “Sandwich Generation” sounds polite, almost clinical. But for the millions of adults living it, the reality feels a lot more like a pressure cooker. They are squeezed tight. On one side, there are children needing help with homework, permission slips, and growing pains. On the other, aging parents need support with doctors, medications, and a lifetime of accumulated paperwork.
It is exhausting.
The hardest part usually isn’t the physical caregiving. It is the administration. It is being the unpaid, overworked secretary for two different households. One minute, a parent is hunting for a vaccination card for summer camp; the next, they are frantically searching for Mom’s Medicare supplement number because a receptionist is waiting on the line.
When these worlds collide, chaos wins. Unless, of course, there is a system in place.
Two Households, One Overloaded Brain
The main problem isn’t a lack of effort. It is a lack of centralization. The “Sandwich” caregiver is trying to run two different operating systems at once.
Consider the children. Their documentation is constant and urgent:
- Social Security cards (usually lost in a drawer somewhere).
- Immunization records that schools demand every September.
- Birth certificates for sports or travel.
Then look at the parents. Their paper trail is decades long and much heavier:
- Wills, Trusts, and Deeds (often hidden in “safe” places that no one can find).
- Complex lists of daily medications.
- Insurance policies that need to be renewed.
- The dreaded “In Case of Emergency” contacts.
Keeping the kids’ files in a backpack and the parents’ files in a dusty filing cabinet across town simply doesn’t work. Not in 2026. When an emergency happens, and they always happen at inconvenient times, nobody wants to be driving across town to find a piece of paper.
The “Kitchen Table” Talk
Getting organized starts with a conversation, not a scanner. This is the tricky part. Many adults feel awkward asking their parents about wills or bank accounts. It feels intrusive.
But the conversation doesn’t have to be about control. It should be about safety. The approach matters. Framing it as, “We need to make sure the doctors know what you need if you can’t tell them,” works a lot better than, “Give me your passwords.”
The goal is strictly practical: preventing a crisis from becoming a disaster.
Cut the Clutter: What Actually Matters?
A common mistake is trying to save everything. But honestly, nobody needs to digitize a utility bill from 1998. To survive the squeeze, caregivers need to be ruthless about what they keep.
The “Must-Have” list is actually quite short:
- The Legal Shield: Power of Attorney. This is non-negotiable. Without it, an adult child is legally a stranger to their parent’s bank or doctor.
- The Medical Snapshot: A simple, updated list of what pills they take and who their primary doctor is.
- The Money Trail: Just a list of where the accounts are. Not necessarily the balances, but the locations of the banks and insurance policies.
Stop Relying on Physical Folders
Paper is fragile. It burns, it tears, and most importantly, it stays in one place.
If a parent falls ill while the caregiver is on vacation, that physical folder in the hallway closet is useless. This is why moving to a digital system is the only logical step for a modern family.
Using a secure, encrypted platform, like InsureYouKnow.org, solves the geography problem. It puts the information in the cloud, protected by encryption that is tougher than any lock on a filing cabinet. It means the right information is available on a smartphone, right in the hospital lobby, exactly when it is needed.
Don’t Go It Alone
There is a hero complex in the Sandwich Generation. Everyone tries to carry the load solo. But that is a recipe for burnout.
Once the records are digital, they should be shared. A spouse, a reliable sibling, or a family attorney needs access, too. Modern digital vaults allow for this kind of “trusted partner” access. It ensures that if the primary caregiver gets the flu or gets stuck in a meeting, someone else can step in and handle the situation.
Finding Some Peace
At the end of the day, organizing these records isn’t really about paperwork. It is about buying back time.
Every minute saved by not hunting for a lost insurance card is a minute that can be spent actually being a parent or a son or daughter. The paperwork will always be there, but the stress doesn’t have to be. By merging these two chaotic worlds into one secure place, the Sandwich Generation can finally take a breath.
Divorce & Data: How to Split Your Digital Life Safely
December 26, 2025
The Digital Aftermath
Breaking up used to mean splitting the vinyl collection and deciding who keeps the couch. Simple. Tangible. But today? The most complicated part of a separation isn’t sitting in the living room; it’s floating in the cloud.
We live online. A marriage in 2025 is basically a massive web of shared Netflix logins, joint bank apps, Amazon purchase histories, and thousands of photos on a server somewhere. This is the “Digital Split,” and honestly, it is messy. If people ignore it, they risk more than just awkwardness. They risk security leaks, drained accounts, and losing memories that actually matter.
Untangling this web takes a bit of grit, but it has to be done. Here is the playbook for separating a digital life without everything crashing down.
1. The Audit (Or: Seeing the Mess)
Before changing a single password, stop. Take a breath. You can’t fix what you can’t see. Most couples are far more digitally enmeshed than they realize. The first move is a simple audit.
Sit down and write it out. All of it.
- The Money: It’s not just the big bank account. Think Venmo, PayPal, crypto wallets, and those “buy now, pay later” apps.
- The Boring Stuff: Who pays the electric bill? Whose email is on the mortgage portal?
- The Fun Stuff: Spotify duos, Netflix profiles, gaming accounts.
- The Doorstep: Uber, Lyft, DoorDash.
Imagine the chaos if one person kills a shared credit card on Amazon without saying a word. Subscriptions bounce. Deliveries get canceled. It’s a headache nobody needs right now. Awareness is the best defense.
2. Locking the Virtual Doors
Once the list is ready, it’s time to secure the perimeter. Financial data is vulnerable, and emotions can make people do rash things.
For personal accounts like email, private checking, and social media, the passwords need to change. Today. And please, no more using the dog’s name or that old anniversary date. Pick something random.
This is also the moment to turn on Two-Factor Authentication (2FA) everywhere. It’s annoying, sure, but it’s a lifesaver. Even if an ex-partner guesses the new password, they can’t get in without the code sent to the phone. Also, dig into credit card apps and check for “authorized users.” If that isn’t cleared up, one person could be stuck paying for the other’s post-breakup therapy shopping.
3. The Photo Dilemma: Keep, Don’t Delete
This hurts the most. Who gets the pictures? The wedding video? The baby photos? Unlike a physical album, nobody has to lose out here.
The rule is strict: Duplicate, don’t delete.
Legally, wiping a hard drive or deleting a cloud account can be seen as destroying assets. It’s a bad look in court. Instead, buy a big external hard drive. Download everything, every shared memory, and hand the drive over. Or, use Google Photos to make a massive shared album, let them download it all, and then cut the link. Everyone walks away with their memories intact. No data lost.
4. Cutting the Invisible Ties
Then there are the things running in the background. The invisible tethers.
Check location sharing. Apps like “Find My” or Google Maps are great for knowing when a spouse is home for dinner, but after a split? It’s just surveillance. Unless there’s a solid reason to keep it on, like co-parenting coordination, shut it down.
The smart home is another trap. If one partner moves out, they shouldn’t still have the code to the front door or access to the Nest cameras. Watching an ex-partner come and go via a phone screen isn’t healthy for anyone.
5. The “Legacy” Check
It’s dark, but it matters. Check the beneficiaries.
Life insurance, 401(k)s, and investment apps all have that little “Transfer on Death” field. People fill it out once and forget it exists. If it isn’t updated, an ex-spouse could technically inherit money meant for kids or a new family ten years from now. It takes five minutes to fix, but it saves a lifetime of legal trouble later.
Final Thoughts
Separating a life is heavy work. But in this era, the digital separation is just as heavy as the physical one. It’s about privacy, security, and eventually, peace of mind. By locking down the data and safely copying the memories, the path forward gets a little bit clearer.
Pull the last three months of bank statements. That’s usually where the hidden subscriptions are hiding. Good luck.
Why Freelancers Need Vault for Business, Insurance and Personal Docs
December 3, 2025
Running a small business or working independently as a freelancer can be incredibly rewarding, but it also comes with a unique kind of pressure. There is no support team to handle accounts, filing, legal paperwork or insurance policies. Everything falls on one person. And when documents get scattered across laptops, email inboxes, envelopes, and drawers, that pressure doubles.
Many professionals don’t realise the value of having one organised vault for business, insurance, and even personal documents until something goes wrong like a tax review, a lost invoice, a sudden medical emergency or an unexpected client dispute. Situations like these can turn a normal week into chaos if the necessary files aren’t available when they’re needed.
The Hidden Risk Behind Scattered Paperwork
Almost every freelancer or business owner ends up collecting a long list of important documents over time:
- Contracts and NDAs
- Tax records and GST filings
- Business registration and licenses
- Insurance policies
- Personal documents like PAN / Aadhaar / passport copies
- Client invoices and payment proofs
When these are stored in different places some printed, some emailed, some saved on a mobile phone, some forgotten on a hard drive it becomes hard to track what exists and what is missing. Searching for one paper in the middle of work is stressful and wastes valuable time that could be spent earning money.
It is not just about convenience scattered documents increase the chances of financial loss, missed tax claims, denied insurance claims and even legal trouble.
Why a Single Vault Makes Life Easier
Keeping all important documents in one vault (preferably digital) can completely transform the way a business operates. A well-organised vault helps in:
Faster Access When Needed
Instead of digging through old emails or piles of files, documents are found in seconds. During tax season, project negotiations, audits or emergencies, this makes an unbelievable difference.
Confidence with Clients and Authorities
Being able to quickly retrieve contracts, invoices or payment receipts shows professionalism. It also protects the business during disputes or late payments.
No More Panic During Emergencies
If a device breaks, a document goes missing or an accident occurs, a vault ensures that everything is backed up and safely stored.
Clear Separation of Personal and Business Finances
Many freelancers mix personal and business papers by accident. Keeping them in labelled folders inside one vault keeps everything organised without confusion.
Which Documents Should Be Included?
A good vault should include every document that is hard to replace, legally important or financially relevant. For example:
Business-related documents
- Licenses and registrations
- Client contracts and project agreements
- Invoices sent and payment receipts
- Expense proofs bills, subscriptions, travel, utilities
- Bank statements and annual reports
Insurance-related documents
- Health insurance policies
- Life insurance details
- Business and asset insurance
- Renewal receipts and claim history
Personal documents
- Identity proofs such as Aadhaar, PAN, Passport
- Important legal documents
- Nominee details
Keeping everything in one vault does not mix the documents it simply allows them to be stored together but categorised, making access extremely efficient.
Digital Vault vs Physical Storage Which Is Better?
Some business owners still rely on physical files, and while that is familiar, it has limitations. Paper can be misplaced, damaged by water or fire and is hard to access when travelling or working remotely.
A digital vault has several advantages:
- Documents can be accessed anytime, even while travelling or from another device
- Multiple categories and labels reduce confusion
- Search options make it easy to locate files quickly
- Backup storage ensures documents are not lost
- Sensitive information can be password protected
For professionals who work across locations or serve international clients, digital access becomes even more valuable.
Real-World Scenarios Where a Vault Saves the Day
A secure, organised vault may feel like an optional system until the moment it becomes essential:
- A client wants to verify payment for an old invoice
- A large company payroll team requests old tax receipts for onboarding
- A medical emergency requires quick access to insurance details
- A visa form needs a scanned copy of passport and financial proof
- A GST or income tax review asks for expense records from previous years
Having everything stored neatly in one place turns stressful events into simple tasks.
A Small Habit That Leads to Big Stability
Building a vault doesn’t require complicated software or a huge investment. It only needs a habit: every time an important document arrives, store it in the vault immediately. Small, consistent organisation protects both personal and professional life in the long run.
For freelancers and small business owners, a vault is not just storage. It is preparation. It is peace of mind. It is a safety net during the uncertain moments that every business eventually faces.
Final Thought
Success in business isn’t only about skills or marketing. It is also about stability and preparedness. Keeping business, insurance and personal documents in one secure vault gives a professional the confidence to grow without fear of losing control over paperwork. With organised records, business becomes smoother, income becomes predictable and stressful situations become manageable.
Newly Married? Important Insurance and Legal Documents to Save Now
November 26, 2025
Most couples spend the first weeks of marriage figuring out things like whose coffee style wins, which side of the bed belongs to whom, and how two different families do holidays. It is fun, chaotic, and full of learning. What usually doesn’t get discussed at first is paperwork. Not exactly romantic, but surprisingly important.
At some point, something small happens that reminds couples that paperwork matters. Maybe the doctor’s office asks for updated insurance. Maybe the bank asks for proof of name change. Maybe a car insurance rep needs beneficiary information right away. Moments like these make people realize how helpful it would have been to organize everything sooner.
So, here is a simple guide to make life a little easier for newly married couples.
Start with the marriage certificate
This one becomes the “key” to a lot of changes. It opens the door to updating names, insurance, bank accounts, and tax filing status. It is worth keeping the original somewhere safe and also scanning a copy so it is easy to find when someone asks for it unexpectedly.
If there is a name change, IDs need updating
Changing a last name takes more effort than most people expect. A few things usually need updating:
- Driver’s license or state ID
- Passport
- Social Security information
Scanning the updated documents helps avoid digging through drawers later.
Review health insurance
Many couples take a look at their coverage after marriage. Sometimes one partner has the better plan, or combining coverage saves money. It helps to keep:
- Current policy papers
- Digital insurance cards
- Provider phone numbers
It is amazing how often those papers are needed during stressful times.
Life insurance becomes part of the picture
No one likes thinking about worst-case scenarios, especially right after a wedding. But life insurance is an act of love and responsibility. Storing the policy and beneficiary information makes sure everything is clear if it is ever needed.
Home and car insurance too
Once couples live together or share a car, insurance companies need updated details. It is easier later if things like renters or homeowners insurance, auto insurance papers, and proof of valuable belongings are collected in one spot instead of scattered everywhere.
Financial documents and beneficiary details
Money looks different once two lives merge. Some couples join accounts. Others keep things separate. Whatever the setup, it is helpful to keep a record of things like:
- Bank info
- Retirement plans and investment details
- Mortgage or loan documents
This stuff can get confusing fast if it is not organized.
Estate planning might sound early… but it matters
Nobody wants to think about wills or medical decisions during the honeymoon stage. Still, life happens, and having things like a will or medical directive stored safely can protect the person you love most. It is one of those things you do hoping it never has to be used.
Where should everything go?
A lot of couples start out with good intentions and then end up stuffing these papers into random folders, drawers, or email attachments. The safest route is somewhere they can always access, even during emergencies, usually a secure digital vault for documents. It keeps things organized, private, and available when life throws a surprise.
A simple takeaway
Marriage brings a lot of joy and a little chaos. While sorting through insurance and legal papers might not feel urgent, it is one of those grown-up things that protects everything two people are building together. Once documents are updated and stored safely, it becomes one less thing to worry about and more energy can go back to enjoying married life.
What Happens If You Don’t Keep Your Insurance Info Updated?
November 19, 2025
Most of us buy insurance with good intentions. We sign the papers, file them away, and honestly, we don’t think much about them again. Life gets busy. Updating insurance info is the kind of task that quietly slips off the radar. But here’s the thing: life changes constantly, and your insurance doesn’t magically keep up.
If your policy stays the same while everything else in your life shifts around, you might end up with coverage that doesn’t match your situation anymore. And that usually shows up at the worst possible time.
Why Keeping Info Updated Actually Matters
Insurance companies depend on accurate details. They decide coverage and pricing based on the information you gave them at the start. If something meaningful changes and you don’t tell them, the policy may not reflect reality anymore.
Think about how often little changes happen: moving to a different place, adding someone new to the family, buying things you’d be upset to lose, fixing up your house, or even having changes at work. None of these moments seem “insurance-worthy” at the time, but they actually matter.
What Could Happen If Nothing Gets Updated
A lot of people assume that as long as premiums are paid, everything is fine. Unfortunately, insurance doesn’t exactly work that way.
1. Claims Might Not Go Smoothly
If something goes wrong and you file a claim, the insurer will check whether your information matches your real situation. If they find a big difference, the claim might get delayed, reduced, or rejected. For example, if your home is worth more because of renovations and you didn’t update the policy, the payout probably won’t cover the full damage.
2. You Might Not Have Enough Coverage
People often don’t realize their coverage is outdated until something happens. Maybe your family has grown, or you’ve bought more valuable items. A policy that once fit perfectly might not come close now.
3. The Policy Could Be Cancelled
Insurance companies expect major details to be accurate. If something important wasn’t updated, they can cancel the policy. In rare cases, they may even say it was never valid.
4. Renewal Might Become Expensive
Sometimes outdated details cause confusion during reviews. Even if the claim goes through, renewal might come with a higher price tag.
5. Stress Piles Up When You Least Want It
Insurance is supposed to offer relief during stressful times. Outdated information can turn that relief into more stress, more paperwork, more delays, and more frustration.
Things Worth Reviewing From Time to Time
It helps to check these once in a while:
- Where you live
- Changes in your family
- Any expensive new purchases
- Home improvements or upgrades
- Vehicle changes or new drivers
- Major health or job changes
- Beneficiaries
A simple yearly check is enough for most people.
Easy Ways to Keep Everything Updated
You don’t need to make this complicated. A few easy habits can help:
- Glance over your policies once a year.
- Whenever something big happens, just send a quick update.
- Keep all your insurance documents in one place so you don’t forget what you have.
- Make a short list of things that typically change over time.
- Ask the insurer when you’re unsure; they’re used to these questions.
Final Thoughts
Insurance is meant to support you when life gets tough, but it can only do that if the information behind the policy reflects your current situation. When details sit unchanged for too long, the coverage weakens and sometimes disappears when you need it most.
A few minutes of updating here and there can save you from a lot of trouble later. It doesn’t take much, but it makes a big difference when life throws something unexpected your way.