Category: Personal Finance
10 Retirement Myths That Could Cost You
November 17, 2026
About 1.7 million workers retire each year in the U.S. From the magic of retiring at 65 to the belief that expenses automatically shrink once you stop working, retirement planning is full of assumptions that don’t always hold up. Some are outdated. Others were never reliable to begin with.
Here are 10 common retirement myths worth reconsidering before you make your next financial move.
1. Myth: You Have to Retire at 65
Sixty-five isn’t a mandatory retirement age. It’s when most Americans become eligible for Medicare, but your retirement date should depend on your savings, health, and personal goals. Some people can retire earlier; others prefer working into their seventies. The key is financial readiness, not reaching a particular birthday.
2. Myth: You’ll Automatically Spend Less in Retirement
No more commuting or work clothes sounds like instant savings. But travel, hobbies, home improvements, and healthcare can quickly replace those expenses. Early retirement years can be particularly expensive as people pursue long-postponed plans. Rather than assuming a smaller budget, calculate what your desired retirement lifestyle will cost.
3. Myth: Social Security Will Disappear
Social Security faces serious funding challenges, but it is unlikely to disappear entirely. According to projections discussed by the Center for Retirement Research at Boston College, continuing payroll taxes could cover approximately 78% of scheduled benefits in 2032 if lawmakers make no changes.
Financial planner Luke Delorme cautions against letting uncertainty dictate retirement decisions. “These fears often nudge people toward overly cautious choices,” he says. “It seems unlikely, though not impossible, that Congress will reduce benefits for people who are already receiving them. An alternative would be to hedge this risk by working longer and/or saving more. This option may not be palatable for many, but it may be prudent given the possibility that a sizable reduction in Social Security benefits could derail their plans.”
Planning for potential benefit reductions makes more sense than assuming you’ll receive nothing.
4. Myth: Medicare Covers All Healthcare Expenses
Medicare provides important coverage, but it isn’t comprehensive or free. Premiums, deductibles, dental care, hearing aids, and many vision services can create substantial out-of-pocket costs. Most long-term custodial care isn’t covered either.
Research cited by the Center for Retirement Research suggests about 80% of retirees will require some form of long-term care. Building healthcare expenses into your retirement budget is essential, even if you’re currently healthy.
5. Myth: You’ll Pay Less in Taxes
Leaving the workforce doesn’t necessarily mean entering a lower tax bracket. Withdrawals from traditional IRAs and 401(k)s are generally taxable, and pensions, investment earnings, and Social Security can increase your tax liability.
Depending on your income, up to 85% of your Social Security benefits may be subject to federal income tax. Consider tax diversification and strategic withdrawals before retirement rather than discovering unexpected liabilities afterward.
6. Myth: You Should Claim Social Security at 62
Age 62 is the earliest most people can claim retirement benefits, but claiming immediately permanently reduces monthly payments compared with waiting until full retirement age.
Delaying benefits until age 70 can substantially increase your monthly check. However, claiming early may make sense for someone with health concerns or immediate financial needs. Evaluate your life expectancy, marital status, and other income sources before deciding.
7. Myth: Retirement Investments Should Be Completely Risk-Free
Moving everything into cash and bonds might feel reassuring, but excessive caution carries its own risks. Inflation gradually erodes purchasing power, and retirement could last three decades.
“Abandoning stocks in favor of cash or low-yielding bonds may feel safe but it introduces the real risk of outliving your money,” Delome explains.
A diversified portfolio can balance stability with the growth needed to sustain long-term spending.
8. Myth: You Need $1 Million to Retire Comfortably
A million dollars sounds like the ultimate retirement milestone. But it’s an arbitrary target. Someone with a paid-off home, modest expenses, and reliable pension income may need considerably less. Someone with expensive lifestyle expectations may need substantially more.
Your actual retirement number depends on projected spending, available income, inflation, and longevity. Focus on how much income your savings can reliably provide rather than chasing a round number.
9. Myth: You Can Always Work Longer if You Haven’t Saved Enough
Working longer can strengthen retirement finances, but it isn’t always an option. Health problems, caregiving responsibilities, layoffs, or workplace changes can force retirement earlier than expected.
Treat additional working years as a potential advantage, not your entire backup plan. Increasing savings while you’re employed and preparing for unexpected income disruptions provides greater security.
10. Myth: Retirement Is All About Having Enough Money
A healthy bank account doesn’t automatically guarantee a satisfying retirement. Losing the daily structure, social connections, and identity associated with work can be challenging.
Retirement expert Christine Benz, director of personal finance and retirement planning at Morningstar, emphasizes the psychological adjustment involved in shifting from saving to spending: ” You come to identify yourself as a disciplined saving person,” he says. “I can imagine that it feels very uncomfortable to see your balance go down at all. So, I think there’s a huge mental hurdle to be jumped over.”
Beyond finances, consider how you’ll spend your time, maintain relationships, stay active, and find purpose. Retirement requires thoughtful decisions about income, healthcare, investments, and lifestyle. The goal is to build the financial flexibility and personal fulfillment to enjoy the years that follow.
Save on Everyday Expenses Like a Financial Expert
October 15, 2026
If the cost of everyday living is overtaking your paycheck, you can take steps to get a handle on your finances and reduce financial stress. A recent study by Edward Jones and Gallup found that 83% of Americans experienced financial stress, strain, or uncertainty within the last year. Half of the respondents said they were not in a financial crisis, but were not fully confident.
The first step to feeling more in control of your financial situation is figuring out whether your income covers all your expenses. It seems simple, but the sooner you look at your budget, the more options you’ll have to make the most of your money.
Creating a Better Budget
Every budgeting method follows the same basic principle: making sure your spending doesn’t exceed your income. Creating a budget lets you see where you can cut spending.
“Seeing where your money is going every day can make you aware of unnecessary purchases that you may be making,” says Jennifer McDermott, a consumer advocate at finder.com. “Plus, cutting out those extra daily purchases can help you put aside more money for the future.”
First, be realistic about what you actually spend and how much you can save each month. Don’t set your savings goal too high and then feel deprived. By grouping your spending into categories, you can easily see where you are spending too much. Also plan for the occasional curveball, and always keep some funds set aside for emergencies.
Auditing Your Subscriptions
A recent CNET poll found that the average American is spending $111 monthly on unused subscriptions. Taking time to review your monthly charges and cancel services you’re not using could free up significant money for your budget and savings.
“Grab some paper or make a spreadsheet and list any recurring expenses that you might be able to cut,” says Byron Ellis, a certified financial planner with United Capital Financial Life Management. “Also list any high expenses that you might be able to reduce.”
Don’t just look at recurring streaming charges. Review your insurance policies and any memberships, such as a gym. If you rarely go to the gym, consider canceling and using free online workout classes and walking more outside instead. Many services allow you to pause your subscription without canceling if you’re hesitant to let something go altogether.
Having Savings Goals
You will be far more motivated to save if you set clear and achievable savings goals for yourself. Instead of just trying to save a certain amount of money, a savings goal helps you remember what you’re saving for. Whether it’s buying a new home, paying off student loan debt, or starting a business, figuring out exactly how much you need and how long it will take is the first actionable step.
Then, set up a recurring direct deposit into your savings account. “Automate weekly savings for small amounts you won’t miss, even as little as $10 or $20 per week,” says Andrea Woroch, a nationally recognized consumer expert. “These small amounts will build quickly over time, and you will learn to live without those extra funds.” By shopping around, you can find a savings account with the best interest rates, which can really boost your savings too.
Cutting Costs at Home
According to the Energy Saving Trust, lowering the thermostat by just one degree Celsius (about two degrees Fahrenheit) can cut your annual bill by up to 10%. Turning off heating or cooling in unused rooms, or programming the temperature to adjust accordingly, can noticeably reduce your energy costs. Switching to LED bulbs can also significantly reduce your home’s lighting costs. Modern LED lightbulbs last up to 25 times longer than traditional lightbulbs and use about 70% less energy, making them worth the upfront investment.
Make sure you’re unplugging everything when it isn’t being used, including TVs, laptops, coffee makers, and cable boxes. In fact, the U.S. Department of Energy estimated that leaving these unused appliances plugged in can account for 5–10% of the average home’s electrical use. “They continue to suck energy even when turned off, which adds to your energy bill,” says Woroch. In certain areas, power strips make it easier to turn off multiple electronics at once, such as at a desk or TV area.
Saving on Fuel
Speeding, accelerating quickly, and braking at the last minute all increase fuel consumption. Properly inflated tires help you get the most out of each tank, and regular servicing can prevent a more expensive repair down the road.
With a fuel price comparison app, you can easily find the lowest fuel prices near you. Reader’s Digest recommends using GasBuddy or the navigation apps you likely already use, including Google Maps and Waze. Even small savings can add up for frequent drivers.
Rethink Social Activities
Talk with your family and friends about your financial stress and the changes that may need to happen at home. Loved ones can be great listeners and may help you find creative ways to save money. According to a Forbes poll, 59% of people said they need to save more money, so your friends are likely in the same boat. Try taking turns hosting potluck dinners or game nights, which are much cheaper than going out to a bar or restaurant.
Meal planning for your weekly dinners in advance can also lead to serious savings on groceries and eating out. Having homemade meals to look forward to can help you avoid the mid-week takeaway temptation. If you and your spouse or partner are on a budget, you can encourage each other by sticking to your savings plans and coming up with creative, low-cost activities you’ll both enjoy.
At Insureyouknow.org, you can keep track of your budget and savings goals in one place. By taking control of your finances, you can ease financial stress and start looking forward to the goals you’ll achieve down the line.
Choosing the Right Debt Payoff Strategy
August 15, 2026
According to data from Capital One, the average American was carrying nearly $6,600 in credit card debt as of May 2026. Based on the Federal Reserve’s estimated average credit card rate, carrying that amount of debt can cause a consumer more than $1,500 in interest over a two-year payoff period.
Debt can become so overwhelming that many begin to view it as something they’ll just never get out from under. They deal with it only by avoiding it at all costs. But with the right approach, anyone can become debt-free. Here are proven strategies to help you get out of debt, repair your credit, and help you regain your financial freedom.
Ways to Stop Incurring Debt
While it may seem like a given, the first step to getting out of debt is to stop incurring debt. To avoid incurring additional debt, have and maintain a realistic budget that reflects both your expenses and debts owed.
When you have debt, you are making interest payments toward that debt instead of using your cash flow for other financial goals. Sticking to a budget can help you reset financially and motivate you to stick to your plans, such as saving up for a home.
One of the best ways to avoid getting into debt in the first place is to keep an emergency fund. An emergency fund is a reserve of cash that is set aside for unplanned life events. A common rule is to save up between three and six months of your expenses.
“Unfortunately, debt tends to snowball. There just has to be a prioritization of saving that emergency bucket so that this doesn’t happen again,” says Cassandra Rupp, a senior wealth advisor and certified financial planner at Vanguard. “The first thing I would always say is just making sure you have that emergency savings bucket.”
Similar to an emergency fund, insurance can help you in the face of unexpected events. Having renters insurance or adequate homeowners coverage and good car insurance can keep you out of catastrophic financial trouble if you face property damage or loss.
Choose Your Strategy
If you really want to get out of debt, then you have to make paying off your debt a top priority. “It takes a lot of stress off of your shoulders to sit back and make a plan,” says Rupp.
Start by knowing not just how much total debt you owe, but also how each debt incurs interest, fees, or penalties. Create an itemized list of every debt you’ve incurred.
“It’s important not to wallow in guilt, shame, or frustration about your debt,” says Austin Kilgore, an analyst at the Achieve Center for Consumer Insights. “Just stick to the facts. Write it all out or use a budgeting tool, so you can really understand the extent of your debt.”
If you prioritize paying off high-interest debts first, then you can avoid paying more in interest fees over time. But if you think some small wins will motivate you, then begin with small bills you know you can pay now. The first approach is the Avalanche Method, while the second is the Snowball Method.
Here’s a breakdown of each strategy.
- The Avalanche Method: This method is most beneficial for those with large debts and high interest rates. Begin by listing your debts from highest interest rate to lowest. Then make minimum payments on each debt, except for the one with the highest interest rate. Use all of your extra money to pay off the debt with the highest interest rate first. Repeat this process each month, after paying off each debt with the highest interest rate. This strategy will save you money and interest, and in the long term, you will pay less to get out of debt.
- The Snowball Method: This method allows people to experience some quick wins by eliminating their smaller debts first. This strategy would be most effective for someone who has many small debts or who needs motivation to gain momentum. Begin by listing your debts from smallest to largest. Make minimum payments on each debt, except the smallest one. Use all of your extra money to pay off your first debt, and repeat this process monthly after paying off the smallest debt.
Negotiating with Lenders
By working with your creditors and lenders directly, you may be able to negotiate a settlement or better repayment plan. If you choose to go this route, speak with a manager who has the authority to adjust your repayment terms and always get a copy of your agreement with them.
Be cautious of companies that assist with debt management and always do your research to make sure the company’s offers are legitimate. Companies that provide debt management services usually do so in three ways: through debt consolidation and debt settlement services for individuals or debt collection for lenders and creditors.
The Role of Debt Companies
With debt consolidation, the borrower pays their full debt balances with a new loan. Debt consolidation is a way to streamline your loans and reduce monthly payments. But this approach is only best if you can get a loan at a lower interest rate. If not, you’re just moving your debt around without making any progress.
Debt settlement involves hiring a company to negotiate lower payments with your creditors, instead of paying the total outstanding balance. These companies usually charge a fee of between 15 and 20 percent of your total debt amount. That means that if what they save you is equal to or less than what they charge you, then they’re not offering you a very good deal.
If you are ever contacted by a debt collection company, make sure the debt is valid before you pay anything. If you think there is an error of any kind, do not pay anything and dispute the debt.
Last, meet with financial experts at your bank or credit union for free guidance. A financial coach at your bank or credit union can help you decide which debt payoff strategy is best for your situation.
Choosing What’s Best
The best debt consolidation method may be the one that best suits your personality. “There’s not a one-size-fits-all approach to dealing with debt,” says Kilgore. “The best debt payoff strategy is the one you’re going to stick with and see through to the end. Full stop.”
If you are someone who thinks mathematically, then The Avalanche Method, in which you pay off your highest interest rate first, is going to make you feel more accomplished quickly.
But if you know you’re going to need fast, noticeable changes in your debt situation, then The Snowball Method is better for you. This strategy feels good immediately, even though it will take you longer to pay off your debt.
At Insureyouknow.org, you can store all of your financial records in one place, including your budget, itemized list of debts, and payment strategy logs. By remaining organized and prioritizing your debt payoff plans, your financial goals will become realities.
Buying a Home When Interest Rates are High
August 1, 2026
If you’ve been waiting for mortgage rates to fall before buying a home, you’re not alone. Experts say the decision isn’t as simple as waiting for lower rates. The better question is whether buying makes sense for your finances today.
According to a recent Rocket Mortgage survey, nearly 60% of Americans said that they would not start looking for a house now. The top three reasons for staying out of the market are high home prices, insufficient savings, and high mortgage rates. In the last five years:
- Home prices increased from $368,000 to $411,000;
- Mortgage rates increased from under 3% to over 6%; and
- Household debt increased from $96,000 to $105,000, while average wages adjusted for inflation remained flat.
Evaluate Your Situation
Mortgage rates generally move with the yield on 10-year U.S. Treasury notes, which are influenced by investor expectations and Federal Reserve policy. As of June 2026, an average 30-year fixed-rate mortgage rate stood at 6.58%. The Fed lowered the rate three times in 2025, but has kept the rate stable so far this year. “It’s not just about rates for homebuyers, but rather the full financial picture of buying,” said Lisa Sturtevant, chief economist at Bright MLS. “Home prices hit record highs this summer in many markets across the U.S. while higher gas prices and concerns about overall inflation rising have created more financial strain for would-be buyers.”
Here are some factors to consider when deciding whether to buy:
- Stability: Do your job and your paycheck seem secure? Do you intend to stay in one place for several years?
- Lifestyle: Can you afford the inevitable maintenance, repair, and insurance costs that come with owning a home?
- Savings: Do you have enough for the down payment, closing costs, moving expenses, and other expenses (e.g., title searches, home inspections, attorney fees)?
- Debt: How much debt (student loans, car payments, credit cards, medical bills) are you carrying?
- Credit: Is your credit score in the neighborhood of 740 or above?
“If your finances feel shaky — for example, you’re worried about job security or paying bills — it’s wise to hold off,” advises Abby Badach Doyle of NerdWallet. “If your income is steady and your budget says the numbers work, don’t let scary ‘what if’ headlines throw you off track.”
Know What You Can Buy
Before you set your sights on your dream home, do some research to answer the following questions:
- Can you increase your income, or reduce your expenses, or both?
- How much can you pay toward a down payment?
- Would you consider buying in a lesser-known area or an area further from your job?
- Are you looking for a fixer-upper, an older home, or new construction?
- Would you consider a condo or a townhome, rather than a single-family home? If so, don’t forget to factor in the HOA fees.
- Are you a veteran? If so, you might qualify for a VA loan, which has some advantages over a regular bank loan.
- Would a 15-year mortgage be more suitable than a 30-year mortgage for your situation?
- Would you consider an adjustable-rate mortgage, as opposed to the standard fixed-rate mortgage (with the commitment to refinance when the rate goes down)?
- Is a rate buydown — in which you pay up front to lower the interest rate — within your budget?
Seek Professional Help
The U.S. Department of Housing and Urban Development (HUD) works with non-profit organizations that counsel homebuyers. Check with the Consumer Financial Protection Bureau for guidance. Licensed real estate agents have expertise in local markets. Loan officers at banks and credit unions can help, as can real estate brokers licensed through the Nationwide Multistate Licensing System.
Prepare for a Worst-Case Scenario
A survey by Clever Real Estate found that nearly half of new homeowners struggled to make mortgage payments and took on additional debt because they:
- Purchased a home over their budget;
- Accepted a higher interest rate than planned;
- Compromised on their priorities, especially home prices; and
- Confronted excessive maintenance costs.
Although your basic mortgage payment will be locked in for the life of the loan, all other costs associated with buying and owning a home will increase over time. The best scenario for a homebuyer is for both interest rates and home prices to drop, but it is hard to predict when (or whether) those two factors will coincide. Experts can calculate potential trends based on past and current data, but you can’t plan to buy a house based on what the mortgage rate might be in three years.
“The truth is, the right time to buy is when it makes sense for you,” says Doyle.
How to Tell Your Beneficiaries About Life Insurance Without Stress
March 19, 2026
Billions of dollars in life insurance death benefits sit unclaimed across the United States annually. Families often desperately need these funds, and the policies themselves remain completely valid. The problem usually stems from a simple communication gap where the named individuals had no idea the coverage even existed.
Industry investigations revealed major insurers releasing over $7 billion in previously forgotten benefits between 2006 and 2016, but only after regulators forced them to cross-reference death records. Experts strongly believe the actual amount of missing money is substantially higher. Current data points to roughly $6 billion in unpaid benefits sitting in limbo, largely caused by outdated contact details and uninformed relatives.
This situation is entirely preventable. Fixing the issue does not demand expensive attorneys, formal family meetings, or highly uncomfortable discussions. Policyholders just need to share the right details clearly and proactively so the information actually sticks.
Why Beneficiaries Remain in the Dark
Policyholders avoid talking about their coverage for several reasons. Some individuals harbor superstitions regarding death. Others fear the topic might sound morbid or cause unnecessary distress among relatives. A large portion of people simply assume loved ones will figure everything out when the moment arrives.
Insurance providers lack automatic alert systems to notify anyone when a policyholder passes away. No alarm sounds and no automatic check gets mailed. Companies usually only discover a death has occurred when a relative reaches out directly. That requires the family to actually know about the coverage beforehand.
The most frequently forgotten accounts include decades-old plans, employer-sponsored group coverage from previous jobs, and small whole-life policies intended for final expenses. Important paperwork easily gets lost during house moves. Premium drafts might quietly exit a bank account for years without a surviving spouse noticing. Lacking a clear handover of documents leaves surviving relatives guessing and frequently finding nothing.
Starting the Conversation Without Uncomfortable Feelings
Discussing these financial safeguards never has to sound like a grim announcement. Financial planners frequently suggest centering the talk on care and future preparation instead of loss. A simple mindset shift changes everything. The focus moves away from passing away and toward actively protecting important family members.
Several approaches help these talks feel completely natural:
- Tie it to a life event: Welcoming a new grandchild, navigating a health scare, or updating a will provides an easy opening. Someone might say, “While getting these organizational tasks done, it is important to share the details of this life insurance coverage.”
- Frame it as a gift: Informing dependents about their financial protection acts as a generous gesture. Policyholders can position the talk as offering clarity. A good phrase to use is, “To prevent any future scrambling, here are the essential details needed for the records.”
- Use a document review as the opener: Checking financial records every year builds excellent habits. Inviting an adult child or spouse to observe the review creates a low-pressure environment to share policy specifics naturally.
Essential Information for Beneficiaries to Know
Mentioning the mere existence of a policy falls short of being helpful. Grieving relatives require highly specific data to process claims quickly. Handing over this data early minimizes delays, lowers stress levels, and guarantees the funds reach the intended destinations promptly.
The National Association of Insurance Commissioners recommends granting access to the following specific details:
- The exact name of the provider and the full name of the insured person as listed on the contract
- The specific policy number and the exact type of coverage selected
- The total death benefit value alongside any attached riders
- Direct contact details for the provider or the managing agent
- The exact physical or digital location of the official documents
- Clear distinctions between primary and contingent individuals along with the designated percentage splits
Any individual holding multiple plans through an employer, private company, or professional group must document and share every single one. Relatives frequently uncover hidden coverage months or years after a funeral, making thorough documentation crucial.
Explaining Primary and Contingent Beneficiaries Clearly
The difference between primary and contingent designations frequently causes confusion. A primary designation puts a person or entity first in line for the funds. A contingent designation acts as a backup, stepping up only if the primary individual cannot collect the funds due to passing away themselves.
Everyone named on the contract must understand their exact role. Splitting funds requires each party to know their specific percentage share. Transparent communication stops arguments and blocks potential legal headaches later on. It helps to remind everyone that designated beneficiaries on a contract will overrule any instructions written into a standard estate plan.
Keeping Documents Accessible During Critical Moments
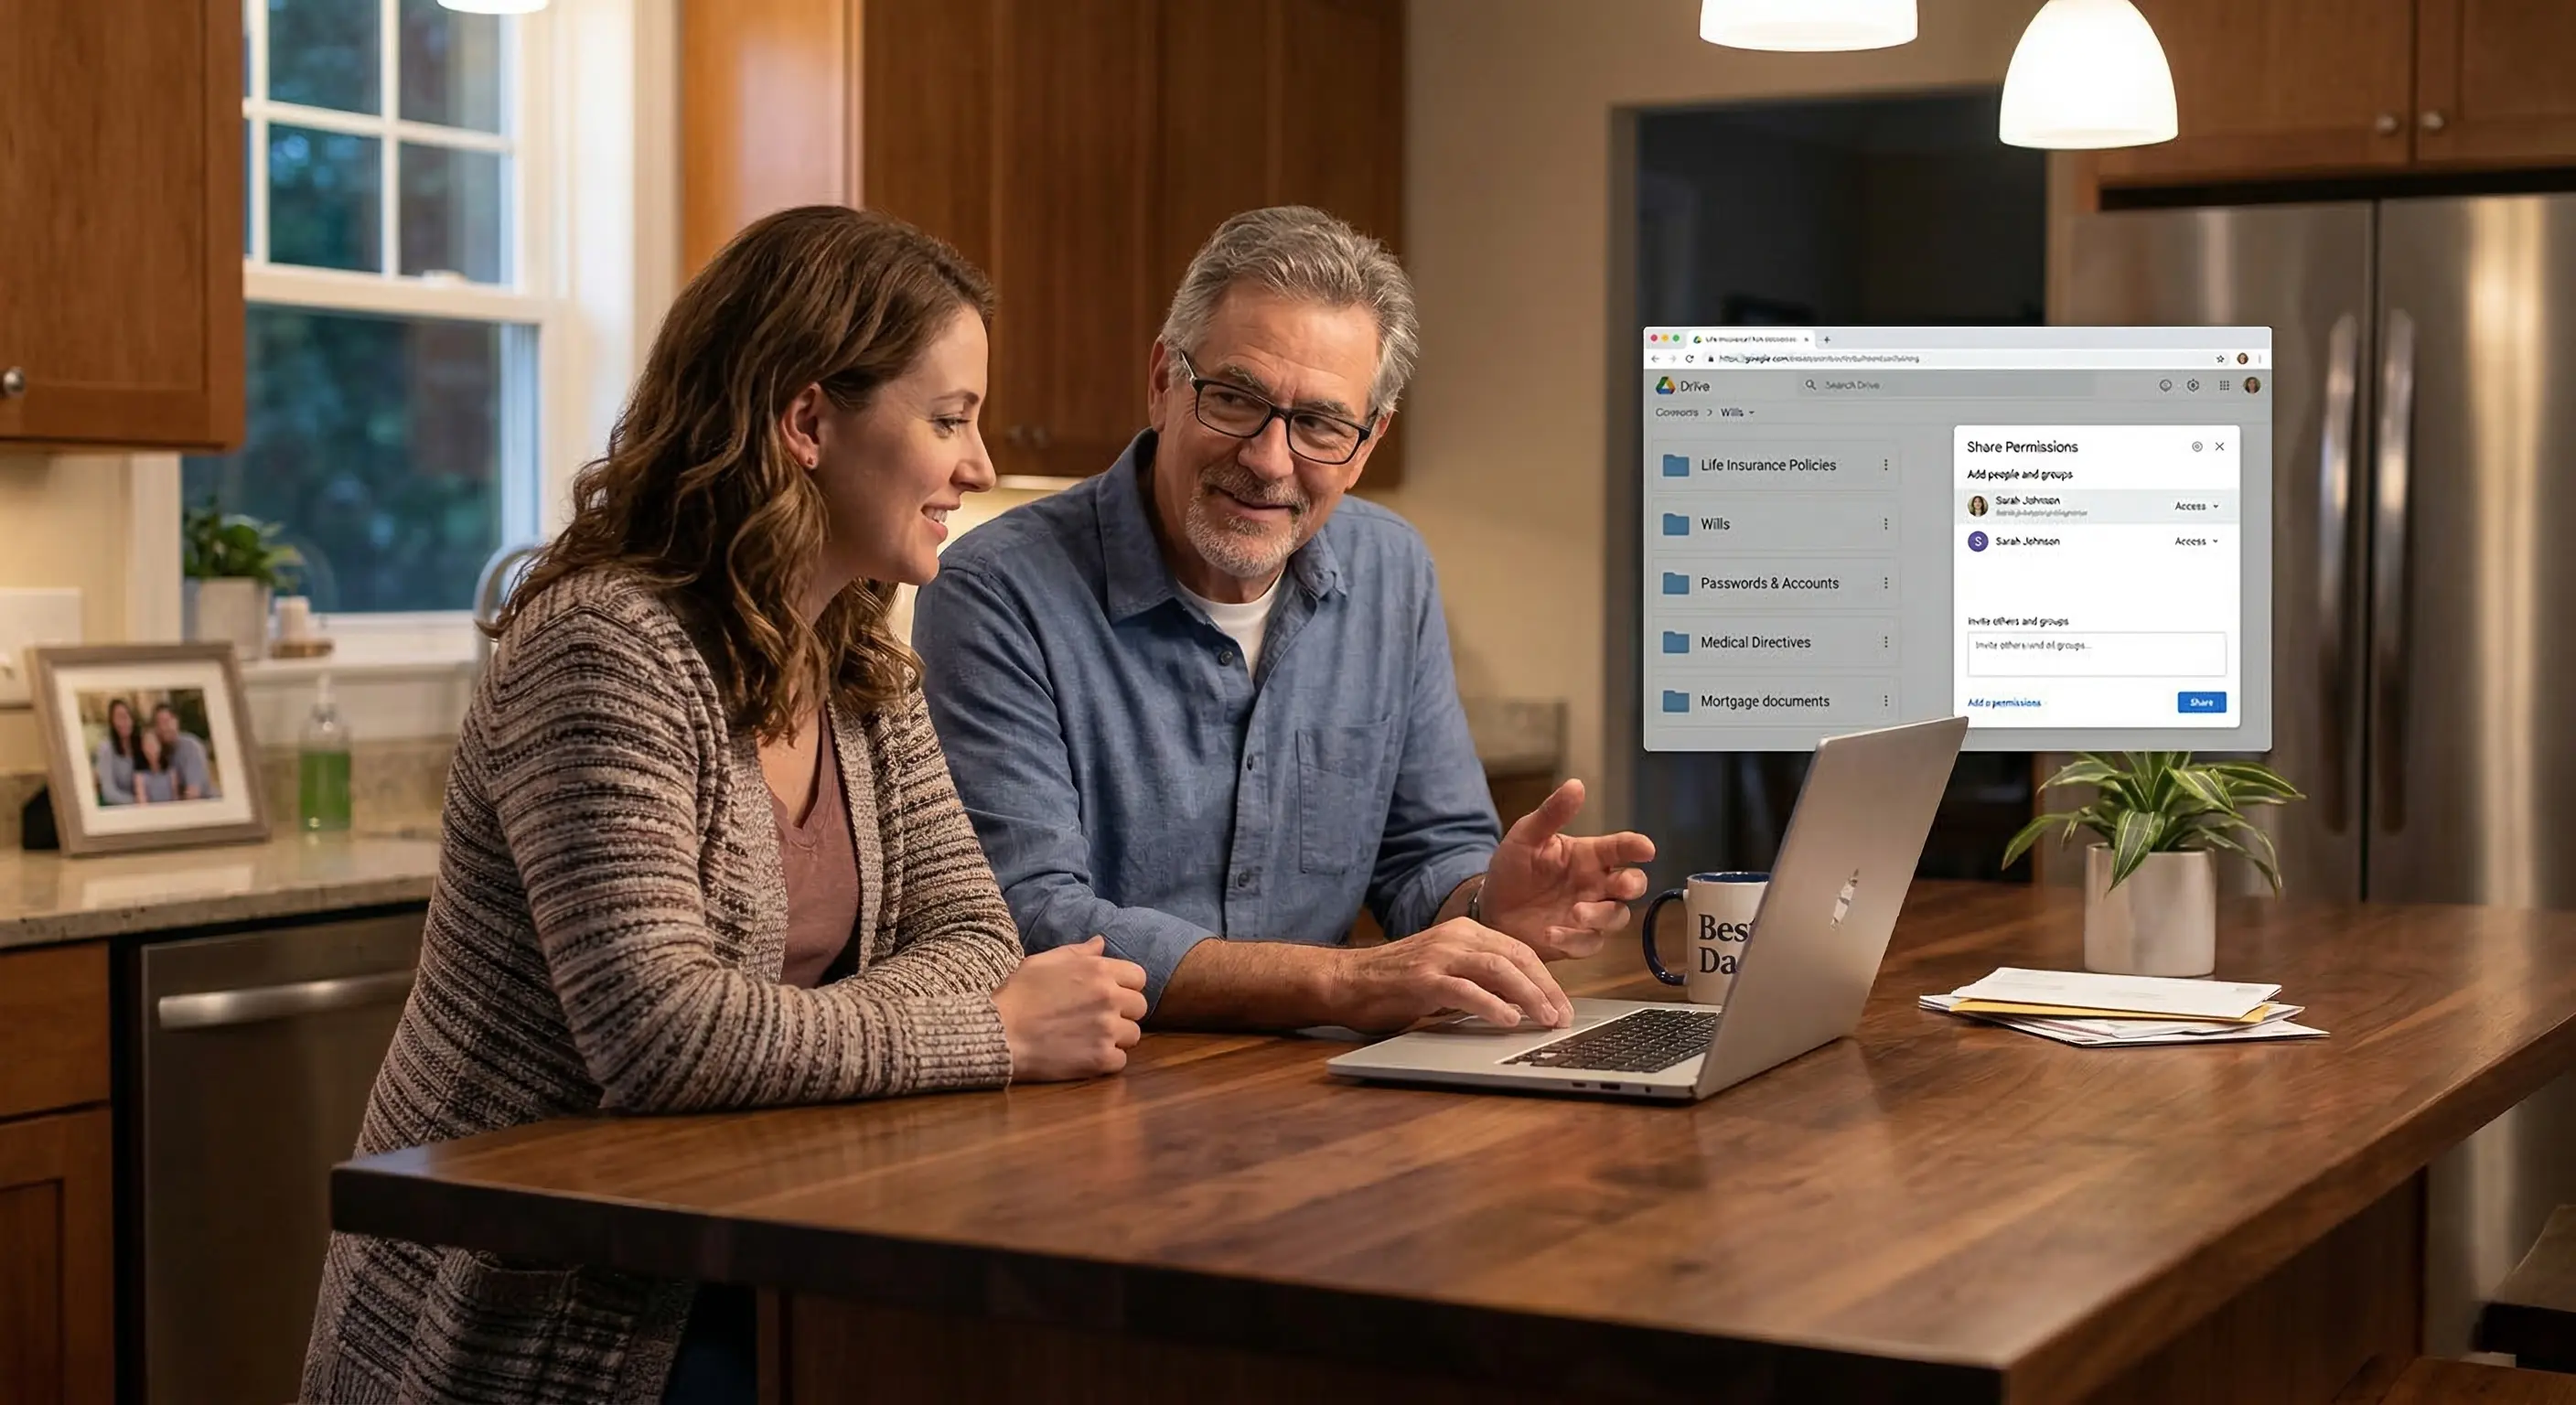
Spoken words offer a solid starting point but fall short long-term. People forget things quickly while grieving. Physical papers easily succumb to fires, floods, or misplacement during a move. The safest strategy pairs direct communication with a highly secure, centralized storage spot for all vital records.
Tucking the contract next to estate papers represents the traditional route, yet it carries flaws. Locking physical copies inside a bank safe deposit box often requires the policyholder to be present for access. This creates massive roadblocks for relatives at the worst possible time.
Digital platforms solve this accessibility problem beautifully. Encrypted online vaults allow users to stash life insurance details, medical coverage, banking numbers, and legal files in a single hub. Trusted contacts receive access to designated files, guaranteeing the correct people find the right information instantly from any location.
Updating Beneficiary Designations and Communicating Changes
Designations must evolve alongside major life shifts. Marriages, divorces, new babies, or the loss of a designated relative demand an immediate contract review. Neglected updates stand out as a top reason for delayed payouts and legal disputes. Industry research shows roughly 8% of claims hit roadblocks specifically due to obsolete contact data.
Updating a file means everyone involved needs a notification. Swapping out a former spouse for a new partner means both sides require an update, when appropriate. These chats might feel slightly awkward, but leaving a grieving family to fight over uncertain terms causes much deeper pain.
Creating an annual calendar alert to verify these designations builds a highly effective habit. Digital platforms often send automated monthly nudges to check for necessary updates. This turns file maintenance into a seamless part of standard financial upkeep.
Early Conversations Protect Loved Ones Tomorrow
Sharing policy details ranks among the most impactful financial steps a person can take. The process requires zero legal background and avoids feeling overly morbid. It just takes a willingness to speak directly and the discipline to organize the supporting paperwork.
Relatives who understand the coverage, know the storage location, and possess the correct contact numbers can actually focus on healing instead of hunting down forms. Providing that exact peace of mind remains the core purpose of buying coverage. The product only works if the protected individuals know it exists.
Utilizing an encrypted digital vault to hold these financial and legal records proves incredibly practical. This ensures the preparation goes far beyond spoken words. It builds an adaptable record that follows a family through every life stage, waiting quietly until the exact moment it becomes necessary.
Property Tax Exemptions for Seniors: What Every Homeowner Needs to Know
March 15, 2026
For local governments in the United States, property taxes are the primary source of revenue. However, property tax has historically been among the most unpopular taxes. In November 2025, the City of Atlanta and Fulton County, Georgia, overwhelmingly approved new homestead tax exemptions for seniors, with 73% of 91,169 Atlanta voters supporting the measure.
As home values rise, property taxes have become a growing burden for homeowners nationwide, particularly for older Americans on fixed incomes. Many of them worry that the property taxes alone will eventually price them out of their homes.
To mitigate this, nearly every state offers a homestead exemption for residential property. However, few seniors realize they may qualify for additional exemptions. “These are very big exemptions,” says Colton Pace, property tax expert and CEO of Ownwell. “It’s an aggressive way to keep seniors in their homes.”
Here’s everything you need to know about state property tax relief for seniors and whether or not you qualify.
How Exemptions Work for Seniors
To ease the financial strain of property taxes, 16 states and the District of Columbia offer exemptions for qualifying seniors. Senior property tax exemptions lower your tax bill by reducing the taxable value of your home.
Alaska, for instance, waives the first $150,000 of the assessed home value for homeowners aged 65 and over, while the District of Columbia cuts property taxes in half for all qualifying seniors.
Most states have a government website dedicated to taxes that lists local rules for senior property tax exemptions. A Google search for “senior property tax exemptions + your state” should find yours.
Don’t Forget Freezes, Credits, and Deferrals
In addition to property tax exemptions, many states also offer:
- Property tax freezes, which lock in your current tax amount, prevent increases down the line if your home’s value rises. Both Arizona and Arkansas freeze the property value of a primary residence for qualifying seniors, preventing increases in assessed value.
- Tax credits provide a direct reduction in your tax bill. Instead of adjusting your home’s value to your tax benefit, credits subtract a set amount from the total you owe. New Jersey’s Stay NJ program, for example, reimburses 50% of property tax bills, with a limit of $6,500, and in Wisconsin, eligible seniors receive both homestead and school property tax credits.
- Deferrals allow seniors to delay paying their taxes, sometimes in exchange for a lien against their home. When the owner dies or decides to sell their home, the state collects the tax debt, often with interest. In Maine, eligible seniors may defer their taxes until after sale or death, and in Vermont, they may also defer their taxes until sale or death, with a 0% interest rate.
Legislation is Ongoing
Many states continue to introduce legislation to expand senior tax benefits. Local governments in both Maine and Ohio are trying to eliminate property taxes for qualifying seniors altogether.
In December 2025, Rensselaer County, in Troy, New York, proposed a law to provide disabled seniors with additional tax benefits. “This law delivers real relief for Troy’s seniors and residents living with disabilities who have been struggling with rising costs,” says Mayor Carmella Mantello. “We are making sure our most vulnerable neighbors can stay in their homes and maintain their quality of life.”
Know if You Qualify
In addition to meeting an age requirement, states also require income brackets to fall within and proof of residence in the home for a certain amount of time. Qualifications vary from state to state and sometimes yearly, so it’s essential to meet with a county assessor at your local clerk of courts or a financial advisor who specializes in retirement.
Putting in the time to know whether or not you qualify for any property tax exemptions can be time-consuming, but well worth the chore. According to a recent report by Realtor.com, as many as 40.5% of homeowners could be overpaying on their property taxes.
Saving Home
Ultimately, these senior property tax exemptions are intended to ease the burden of rising costs during retirement and help keep seniors in their longtime homes and communities. Most seniors live on a fixed income, so when taxes become too difficult to pay due to rising home values, even seniors with moderate incomes can find themselves struggling to remain in the home they’ve spent most of their adult life in.
With Insureyouknow.org, seniors can keep all of their tax research, financial records, and other proof of residential requirements in one organized place. Remember that while it may feel like a lot of work in the beginning to gather this information, you are likely going to save yourself enough money on those pesky property taxes to make it well worth it.
2026 OBBBA Estate Tax Changes: What Families Must Update
March 11, 2026

The wealth transfer landscape just experienced a massive earthquake. When the One Big Beautiful Bill Act (OBBBA) took full effect on January 1, 2026, it completely tossed out the old estate planning rulebook. For years, financial planners, wealth managers, and tax attorneys had been bracing for the Tax Cuts and Jobs Act (TCJA) to expire. Everyone fully expected federal estate tax exemptions to get sliced in half overnight. Instead, lawmakers pivoted. The OBBBA rolled out permanent, historically high exemption thresholds that caught many off guard.
But breathing a sigh of relief and doing nothing is a very dangerous game. The new rules demand a fresh, immediate look at existing wills, family trusts, and generational wealth strategies. Navigating state-level tax cliffs, optimizing new child savings accounts, and securing vital legal documents in an encrypted digital vault are no longer optional steps. Taxpayers have to adapt to this new 2026 reality right now. Otherwise, they risk leaving their family’s financial future completely exposed to unnecessary taxation and legal chaos.
The New $15 Million Federal Exemption
Let us look closely at the numbers. The absolute heart of the OBBBA’s estate planning shift is a massive, permanent bump in federal estate, gift, and generation-skipping transfer (GST) tax exemptions. As of the start of 2026, the baseline sits at a staggering $15 million per person. For a married couple, that builds a $30 million fortress against federal wealth transfer taxes. And yes, those figures are indexed for inflation. They will keep inching up year after year to match economic changes.
Before this legislation passed, a low-level panic had set in among high-net-worth households. Families rushed to execute lifetime gifts, terrified the exemption would drop back down to roughly $7 million. Today, that ticking clock is gone. The absolute permanence of the $15 million threshold lets people slow down. Families can now make smarter, highly calculated, long-term choices about distributing their wealth without an artificial deadline hanging over their heads.
Realistically, only a tiny sliver of the absolute wealthiest estates will ever see that punishing 40% federal estate tax hit. Removing that massive federal tax burden for the vast majority of households changes the entire financial game. The planning focus now shifts sharply toward income tax efficiency and carefully managing assets that grow in value over time.
The Strategic Pivot to Capital Gains and Step-Up in Basis
With federal estate taxes officially off the table for most, a new financial villain emerges: the capital gains tax. This shift makes the “step-up in basis” strategy incredibly valuable. Under the current tax code, when someone inherits an asset think real estate, art collections, stock portfolios, or a family business the tax basis of that asset gets “stepped up.” It adjusts legally to the fair market value on the exact day the original owner passes away.
Consider an individual who bought a commercial property decades ago for $200,000. Today, the market values that property at a cool $2 million. If the owner hands that property to their children right now as a living gift, the kids take on that original $200,000 cost basis. If those heirs turn around and sell the building, they will get slapped with brutal capital gains taxes on $1.8 million of profit.
But what if that same property transfers at death? The heirs receive it with a stepped-up basis of $2 million. They could sell the building the very next day and owe absolutely zero capital gains tax. Because the OBBBA erased the fear of a 40% estate tax for most, holding onto highly appreciated assets until death is now the smartest play. It shields heirs from massive, wealth-destroying income tax bills.
Why Lifetime Gifting Remains Vital for High-Net-Worth Estates
Still, families hovering near or above that $15 million (or $30 million joint) mark cannot just sit back and relax. Lifetime gifting remains a cornerstone strategy for the ultra-wealthy. The basic math of estate planning has not changed one bit. Assets left inside a taxable estate will keep growing. Eventually, that future growth will face the 40% federal estate tax axe.
Moving assets today locks in the current $15 million exemption. It guarantees that any future market growth happens completely outside the taxable estate. Take a $10 million business interest as an example. Placing it into an irrevocable trust today is a smart move. If that business grows to $25 million over the next ten years, that entire $15 million of growth is totally safe from federal transfer taxes.
High-level tools like Spousal Lifetime Access Trusts (SLATs) and Generation-Skipping Dynasty Trusts are working harder than ever under the OBBBA. They let families use the big exemptions while keeping assets safe across multiple generations. However, pulling this off requires a mountain of complex legal paperwork. Keeping those irrevocable trust agreements highly secure and instantly accessible is the only way to ensure these sophisticated strategies actually work when the time comes.
The Hidden Trap of State-Level Estate Taxes
Here is a massive trap waiting to spring on unsuspecting families. The federal government eased up, but state governments definitely did not. Assuming the $15 million federal shield protects against all estate taxes is a very expensive mistake. Over a dozen states still enforce their own estate or inheritance taxes. Their exemption limits are usually far, far lower than the federal line.
Take New York’s infamous “tax cliff,” for example. In 2026, if a resident’s estate goes over the state exemption limit by even a fraction, the state taxes the entire estate. The law does not just tax the overflow; it taxes the whole thing. That triggers millions in surprise tax bills. Massachusetts and Oregon also enforce notoriously strict state-level limits.
Families living in or holding real estate in these specific states have to plan locally. Often, this means utilizing aggressive lifetime gifting. Many states with estate taxes completely lack a matching gift tax. Shrinking the taxable estate before death through planned giving can bypass the state tax cliff entirely.
New Provisions: Trump Accounts, 529s, and Charitable Giving
The OBBBA did not just tweak old rules; it brought brand-new tools to the table. Families need to weave these modern provisions into their legacy plans right away to maximize tax efficiency.
- Trump Accounts: A brand-new tax-advantaged setup designed specifically for children. For U.S. citizens born between 2025 and 2028, the federal government drops in a one-time $1,000 seed contribution. From there, families and employers can add up to $5,000 a year until the child turns 18. The wealth grows completely tax-deferred, offering a massive head start on generational wealth building.
- Expanded 529 Plans: Education savings just got a lot more flexible. Families can now pull out up to $20,000 a year for K-12 private school expenses, effectively doubling the old limit. Furthermore, the legal definition of qualified expenses expanded in 2026. Things like private tutoring and specialized textbooks now count, making these accounts far more versatile.
- Charitable Deduction Floors: Starting in 2026, taxpayers who itemize are looking at a new hurdle. Only charitable giving that passes 0.5% of their adjusted gross income actually counts for a tax deduction. This rule forces families to get highly strategic. “Bunching” donations into a single year using Donor-Advised Funds (DAFs) or private foundations is now the undisputed best way to squeeze out maximum tax benefits while supporting chosen causes.
The Critical Need for Digital Organization and Secure Storage
Every time tax laws undergo a massive rewrite, financial advisors sound the alarm. Update the wills. Change the trust terms. Fix the outdated beneficiary designations. But spending thousands of dollars and dozens of hours updating an estate plan is completely useless if no one can actually find the paperwork when tragedy strikes.
The modern estate is no longer just a stack of paper. It consists of digital assets, cryptocurrency private keys, online bank logins, and electronically signed medical directives. Trusting a rusty filing cabinet in a home office or a dusty safe deposit box at a local bank is a disaster waiting to happen. Fires, floods, or simple human error can wipe out years of meticulous legal planning in an instant. When a sudden emergency hits, a chosen digital executor needs fast, zero-friction access to the full financial picture. Hunting down scattered passwords while dealing with grief is a nightmare no family should face.
To make sure a newly updated 2026 estate plan actually works in the real world, families are rapidly migrating to encrypted, independent electronic safe deposit boxes. A centralized digital vault puts life insurance policies, updated trusts, and crucial medical records in one secure spot. Platforms utilizing military-grade cloud encryption and zero-knowledge architecture are the modern gold standard. Why? Because even the host website cannot see the user’s passwords. It guarantees sensitive financial blueprints stay permanently locked away from hackers, yet remain instantly available to trusted, designated contacts during life’s hardest moments.
Conclusion
The 2026 One Big Beautiful Bill Act handed families incredible tools to protect generational wealth. At the same time, it threw complex curveballs regarding capital gains, state taxes, and charity rules. The massive $15 million federal exemption is not an excuse to get lazy. It is a rare opportunity to build smarter, highly tax-efficient strategies. Taxpayers need to sit down with their legal and financial teams to completely overhaul their legacy plans today. And once those plans are updated? They must be locked inside a bulletproof, password-protected digital repository. That is the only way to ensure a carefully built financial legacy survives, stays protected, and activates exactly when the family needs it most.
2026 Student Loan Defaults: Secure Your Financial Records
March 6, 2026
A massive financial wall hit millions of Americans earlier this year. Pandemic payment pauses are officially ancient history. The temporary relief programs dried up entirely. After months of messy court battles regarding income-driven repayment plans, the federal government decided to bring back its heaviest collection tools. Starting in early 2026, the U.S. Department of Education began sending administrative wage garnishment letters to defaulted borrowers. The numbers from major credit bureaus, like Experian, look pretty grim. The entire country is watching a massive wave of loan delinquencies happen in real time. People are suddenly staring down severe financial penalties. Getting through this economic squeeze requires a lot more than just reading news updates. It demands immediate, highly organized access to specific financial paperwork.
The 2026 Student Loan Landscape: A Shocking New Data Trend
So, who is actually defaulting right now? Historically, student loan defaults mostly hammered sub-prime borrowers. That whole narrative flipped completely upside down in 2026. Recent reports from credit bureaus reveal something entirely unexpected. Nearly a quarter of newly defaulted borrowers belong in the “prime” credit tier or even higher. These are the exact demographics the financial industry usually views as incredibly stable.
With over 5 million borrowers currently sitting in default status, and millions more falling behind every month, the economic pain is obvious. Borrowers are stuck navigating a bizarre maze of constantly changing payment plans. Making things worse, millions of accounts got bounced around between different private servicing companies over the last two years. Monthly payments got lost in the mail. Crucial paperwork simply vanished. Hold times to speak with basic customer service stretched into hours. Once a federal student loan reaches 270 days past due, it hits official default status. At that specific moment, the government gets to use an administrative superpower that regular credit card companies cannot even touch. They can literally take wages without ever stepping foot inside a courtroom.
Understanding Administrative Wage Garnishment: The 15% Reality
The fallout from a federal default happens fast. Through a process called Administrative Wage Garnishment (AWG), the Department of Education can legally force an employer to pull up to 15% of a borrower’s disposable pay. Disposable pay simply means the cash remaining after legally required deductions, like federal and state taxes, come out of the check.
Federal law does leave a very small safety net in place. Borrowers get to keep a weekly take-home amount equal to at least 30 times the federal minimum wage. But for anyone living from one paycheck to the next, suddenly losing 15% of their income is pure disaster. It usually means missing the rent, skipping the grocery store, or defaulting on other credit cards. Before the garnishment actually kicks in, the government must send a 30-day advance written warning. That specific 30-day window is basically everything. It acts as the only real timeframe a borrower gets to object or set up a different payment plan before their paycheck actually shrinks.
How to Stop Garnishment: The Heavy Burden of Proof
Borrowers holding a garnishment notice still carry some legal rights. During those 30 days, individuals can officially demand a hearing to stop the withholding order. They might attempt to prove extreme financial hardship. Or, they could try applying for federal loan rehabilitation. Rehabilitation usually involves agreeing to make nine on-time payments over a 10-month window to get the loan back on track.
Another route involves submitting a formal financial hardship appeal. Winning this appeal means legally proving that a 15% pay cut makes buying basic survival items impossible. The government looks at documented living expenses and compares them against very strict IRS Allowable Living Expense guidelines. If a family spends more on food or housing than the IRS thinks is necessary for that specific family size, the extra amount gets totally ignored. Proving hardship is notoriously difficult. Using these rights is never a walk in the park. It requires gathering highly specific legal and financial records immediately. In these types of administrative hearings, the burden of proof lands squarely on the borrower.
The Critical Role of Organized Financial Documents
Sloppy paperwork turns a bad money situation into an absolute nightmare. When the garnishment letter shows up, the clock ticks fast. Spending hours digging through cluttered email inboxes for old messages from loan servicers wastes valuable time. Tearing up the living room looking for utility bills to prove basic living expenses just fuels the anxiety. If a borrower fails to hand over the correct evidence within 30 days, their employer receives the order. The garnishment starts.
This explains exactly why relying on a secure, independent electronic safe deposit box changes the playing field. Keeping a dedicated digital vault for vital life information ensures nobody gets blindsided by aggressive debt collectors. Storing all important financial, legal, and contractual documents in one simple location gives borrowers a huge advantage. They can instantly grab the exact proof they need to protect their paychecks and negotiate with default resolution teams.
Essential Documents to Secure in a Digital Vault
To build a strong defense against a default warning, individuals should make sure the following documents are digitized, safely uploaded, and ready for action:
- Original Loan Agreements and Master Promissory Notes: Finding original contracts immediately helps verify the true debt amount. It also spots accounting errors and confirms which company actually owns the loan today.
- Complete Tax Returns: Proving financial hardship or enrolling in an income-driven repayment plan means submitting paperwork. The Department of Education demands recent federal and state tax returns before they even start talking.
- Official Pay Stubs: Current pay stubs are absolutely required to figure out actual disposable income. They also help verify that any proposed wage garnishment does not illegally drop below the minimum wage protection limit.
- Household Expense Records: Tracking basic living costs is a strict requirement for hardship appeals. Think about rent agreements, mortgage papers, utility bills, health insurance premiums, and pharmacy receipts. These papers help prove that living expenses are reasonable and fit within tight IRS standards.
- Correspondence with Loan Servicers: A strong paper trail of older payments, approved forbearances, and emails with the loan servicers can literally save the day. This proof is extremely important if someone needs to show a loan was wrongfully thrown into default in the first place.
The Absolute Security of Zero-Knowledge Storage
Privacy is absolutely non-negotiable when dealing with highly sensitive financial details. Relying on physical metal filing cabinets leaves people wide open to lost papers, house fires, or basic theft. Depending on regular, unencrypted email folders or a messy computer desktop basically hands sensitive financial data directly to hackers. Cybercriminals routinely target email servers specifically to find W-2 forms and tax returns. Once they grab those files, identity theft is pretty much guaranteed.
Using a specialized platform built with heavy-duty cloud encryption makes sure financial data stays completely private. The absolute best platforms run on Amazon cloud encryption mixed with a “zero-knowledge” setup. In a zero-knowledge system, only the actual account owner knows the password. The site administrators never get to see it. That means absolutely nobody else can ever gain access, view the files, or mine the stored documents to sell the data.
Strategic Document Sharing with Trusted Partners
Fixing a defaulted student loan is almost never a solo job. Borrowers usually need to bring in certified financial planners, tax accountants, or specialized student loan lawyers to help decode the messy federal rules.
Advanced secure portals allow individuals to selectively share specific document folders with these exact trusted partners. Sending unencrypted PDFs of tax returns and pay stubs back and forth through regular email is a massive cybersecurity hazard. Instead, account holders can simply give a legal advisor temporary, secure access to the required files right inside the encrypted vault. This targeted sharing feature speeds up the whole default resolution process, keeps communication secure, and leaves the rest of the vault totally locked down. Setting up automatic monthly reminders inside the portal also helps users routinely update their financial snapshots, keeping their defense strategy completely fresh.
Facing economic uncertainty requires a solid game plan. The return of federal student loan wage garnishments in 2026 creates a massive hurdle. Credit bureau data clearly shows that financial distress is hitting borrowers across every single demographic right now. Surviving this wave of defaults demands aggressive, proactive money management and flawless record-keeping. Centralizing vital financial documents into a secure, encrypted digital safe deposit box lets individuals tackle economic chaos with total confidence. Being prepared is simply the ultimate defense. It ensures that when critical financial information is needed the most, it stays protected, perfectly private, and instantly ready to use.
Passkeys vs. Passwords: Why It’s Time to Switch Now
February 26, 2026
We all do it. Every morning. You grab your coffee, sit down, and try to log into your bank. Or maybe your insurance portal. You type in a password. Maybe it’s a strong one. Maybe it’s… well, let’s be real. It’s probably the same one you use for Netflix. But here is the hard truth: relying on a secret code just doesn’t cut it anymore. Not when your entire financial life is sitting behind it. Fast forward to 2026, and there is finally a better option that people are actually using: the passkey.
If you are the one stuck managing the heavy stuff for your family – wills, health records, the “in case of emergency” file – knowing the difference between a passkey and a password isn’t just tech trivia. It is a survival skill. It’s about keeping the wolves at the door away from the things that actually matter.
This guide breaks down exactly what passkeys are, how they smash the old-school password system, and why making the switch is probably the smartest move you can make right now.
What Is a Password – And Why Is It No Longer Enough?
Think about it. A password is just a string of letters you made up. It’s a secret handshake between you and a computer. And for a long time? That was fine.
But here is the snag: humans are involved. And humans? We are messy. The stats are pretty rough – something like 70% of hacks start because of a weak or stolen login. We reuse passwords because we’re lazy. We pick easy ones because we’re forgetful. Or we get tricked by a fake email and hand them over on a silver platter.
Common password headaches include:
- Brute-force attacks: Hackers have computers that can guess billions of passwords a second. If yours is simple, it’s gone before you can blink.
- The Dark Web: If one random site you use gets breached, your password ends up for sale. Suddenly, the bad guys have the keys to your whole life.
- Phishing: It is terrifyingly easy to get fooled by a fake email or website that looks real. You type it in, and poof – they have it.
- Fatigue: You have dozens of accounts. Remembering unique codes for all of them? Impossible. So we reuse them. And that is dangerous.
- SMS flaws: Even those text message codes aren’t bulletproof. Hackers can swap SIM cards and steal those codes right out of the air.
There is a saying in the security world that haunts me: Hackers don’t break in – they log in. If they have your password, they are you.
What Is a Passkey – And How Does It Work?
Passkeys are a total rewrite of the rules. Forget typing. A passkey uses public-key cryptography. Imagine a digital key that is split in two. One half sits on the website. The other half stays locked inside your phone or laptop.
When you want to log in, your phone and the website have a quick, silent chat. You prove it’s you by just unlocking your screen – Face ID, fingerprint, whatever. You don’t type a single letter. Nothing gets sent over the internet for a hacker to steal.
Think of it like a puzzle. The website has a piece. Your phone has a piece. They only fit together when you – the real you – are holding the device.
Key facts about passkeys:
- They run on the FIDO2 standard. Basically, the big tech companies all agreed on a better way to do things.
- Everyone is jumping on board: Google, Apple, Amazon, Chase Bank. They all support it.
- Millions of people are already using them without even realizing it.
- You can’t phish them. You can’t guess them.
- If you have a smartphone from the last few years, you are already ready to go.
Passkeys vs. Passwords: A Side-by-Side Comparison
Why is everyone making such a big deal about this? You have to look at the differences side-by-side to really get it.
1. Security
- Passwords: Weak. They can be stolen, guessed, or fished out of you with a fake email.
- Passkeys: Rock solid. The private key never leaves your phone. Even if a hacker breaks into the bank’s server, they can’t steal your key because it isn’t there.
2. Ease of Use
- Passwords: A pain. You forget them. You reset them. You type them wrong.
- Passkeys: Easy. You look at your phone, or touch the sensor. Done. It works 98% of the time and it’s way faster.
3. Phishing Resistance
- Passwords: Terrible. If a fake site looks real, you’ll probably type your password in.
- Passkeys: Perfect. A passkey is tied to the real website. If you land on a fake site, your phone knows. It simply won’t let you log in.
4. Device Dependency and Flexibility
- Passwords: You can use them anywhere, but that’s also why they are risky.
- Passkeys: They live on your device. But don’t worry – Apple and Google sync them to the cloud. So your passkeys are on your phone, your tablet, and your laptop automatically.
5. Risk in a Data Breach
- Passwords: If a company gets hacked, your password is leaked.
- Passkeys: If a company gets hacked, the hackers get… nothing useful. They just get a public key that can’t unlock anything without your phone.
Why This Matters for Protecting Vital Life Records
We usually don’t think about this stuff until it’s too late. You get hacked, or a family member passes away and nobody can get into their accounts. That is a nightmare scenario.
The accounts that hold your life’s work – insurance, savings, wills – need better protection than “123456.” If these get breached, it’s not just annoying. It’s identity theft. It’s losing money.
The banks know this. That’s why Chase and Wells Fargo are pushing passkeys. They want you safe.
If you are using a digital vault to keep your family’s info organized, turning on passkeys is the single best thing you can do today.
How to Set Up a Passkey (It Is Simpler Than It Sounds)
You don’t need to be a tech wizard. It takes two minutes.
Step 1: Go to your account settings (Google, Amazon, whatever).
Step 2: Look for “Passkeys” or “Security.”
Step 3: Click “Create Passkey.” Your phone will ask for your face or fingerprint. Do it.
Step 4: You’re done. Next time, just click “Use Passkey.”
Step 5: If you want to be extra safe, use a password manager like 1Password to keep them all organized.
Expert Tip: Start with the big ones. Email. Bank. Insurance. Get those locked down first.
Should Passwords Be Abandoned Entirely?
Not yet. We’re in a transition phase. Lots of old websites still need passwords. So here is the game plan:
- Switch to passkeys for anything important.
- Use a password manager to generate crazy long passwords for the junk sites that don’t support passkeys yet.
- Stop using SMS codes if you can help it. Use an app instead.
- Get a hardware key (like a YubiKey) if you are really paranoid about your email security.
- Check back often. More sites are adding this every month.
Microsoft went passkey-first last year and it’s been huge. By the end of 2026, typing passwords will feel like using a flip phone.
What Happens If a Device Is Lost?
Everyone asks this. “If I lose my phone, am I locked out forever?”
No. You’re fine.
- Cloud Sync: If you use an iPhone, your keys are in iCloud. Get a new phone, sign in, and they are back. Same for Android.
- Backup: You can still use other ways to get into your account if you absolutely have to.
- Thieves can’t use them: Even if someone steals your phone, they don’t have your face or fingerprint. They can’t use your passkeys.
Passkeys and the Future of Secure Document Storage
For families storing wills and financial docs online, security is everything. A digital vault is pointless if the key is under the mat.
Passkeys fix the human error part. You can’t accidentally give away your passkey. It solves the biggest problem in security: us.
Experts at Gartner and big tech firms are calling this the biggest shift in security in decades. The password era is ending. Finally.
Key Takeaways
- Passwords are weak. They are too easy to steal or guess.
- Passkeys are strong. They use heavy-duty encryption and your own biometrics.
- It’s happening now. Major banks and tech giants are already using them.
- Mix it up. Use passkeys where you can, strong passwords where you must.
- Don’t worry about lost phones. Cloud sync has your back.
- Protect your legacy. If you store vital records, this is a must-have upgrade.
Conclusion: The Lock Is Getting an Upgrade
Switching to passkeys isn’t just about cool new tech. It’s about peace of mind. Passwords put all the pressure on you to be perfect. Passkeys let your device handle the security so you don’t have to.
If you are serious about keeping your family’s future safe, stop waiting. Passkeys are here. They work. And they are way better than what you’re using now.
The best time to switch was yesterday. The second best time is today.
Protect What Matters Most
InsureYouKnow.org provides a secure, encrypted electronic safe deposit box for life’s most important information – insurance policies, financial records, healthcare documents, and more. Storing vital records in one organized, protected location means families are never left searching when they need information most. Start protecting what matters today at InsureYouKnow.org.
Preparing for Tax Season
February 15, 2026
Taxes aren’t usually a task people look forward to. If anything, many procrastinate or put the chore off completely. In fact, about 5% of taxpayers fail to file their taxes each year, the top two reasons being that it’s overwhelming or they simply object to paying income taxes. But skipping your taxes is a bad idea.
“It does catch up to you, and the penalties and interest are huge,” says David Ragland, a certified financial planner and CEO of IRC Wealth. “If you don’t file your return, you’re going to have to pay interest on any unpaid taxes.”
The penalty for failing to file is 5% of unpaid taxes for each month a filing is late, capped at 25%. So a taxpayer who owes $10,000 would owe $500 each month, with a maximum owed of $2,500.
Filing your taxes can be intimidating and tedious, but by forming a plan and gathering the documents you need in advance, it can go quite smoothly. Here’s everything you can do to make filing your taxes easier this year.
Gather Paperwork First
Get together all of the information you’ll need for your taxes ahead of filing to save time and reduce stress.
The IRS recommends gathering personal information, including:
- Your Social Security number, as well as those of anyone else on your tax return, such as spouses and dependents
- Your bank account and routing numbers, if you wish to receive your refund by direct deposit
- Your adjusted gross income or AGI and the exact refund amount from last year‘s tax return, if you filed
Anyone who paid you during the year is required to report the payments to the IRS. They must file their information and return forms with the IRS and send a copy to you. You should receive these electronically or by mail in January or February.
These forms include:
- Forms W-2, which show your wages from employers
- Form W-2G for lottery and gambling winnings
- Any Form 1099, including from government payments, freelance and contract work, and retirement plan distributions
- Form SSA-1099 for Social Security benefits
- Form 1095-A, Health Insurance Marketplace Statement
If you are self-employed, have multiple jobs, or have a small business, then you’ll need:
- Bank statements and other payment collection records
- Receipts for potential deductions, such as from travel, car expenses, and business supplies
- Proof of training and further schooling
Anything that you spent on investing in your business is a potential deduction and should be collected as a reference for filing.
Deductions to Know
There’s always the chance that the IRS will file your taxes on your behalf if you fail to file on time yourself. “Just because you don’t file the return doesn’t mean you can escape the IRS long term,” says Ragland. If this happens, you’ll likely miss out on deductions that you yourself would have likely claimed.
Other documents for potential deductions include:
- Childcare and dependent expenses
- Mortgage and property tax records
- Any donations made to charity
- Healthcare expenses, including Health Savings Accounts or HSAs
- Retirement contributions
- Specific education and career expenses, such as those with students and teachers
- Student loan interest statements
The One Big Beautiful Bill Act (OBBB) was signed into law in July 2025 and makes significant changes to the tax code. It makes the 2017 tax cuts (like the seven income tax brackets from 10%–37%) effectively permanent while adjusting many bracket thresholds for inflation and substantially increasing the standard deduction (e.g., $15,750 for singles, $31,500 for joint filers). It also adds new deductions (like for tips, overtime, seniors, and certain auto loan interest), raises the SALT deduction cap, and modifies credits such as the Child Tax Credit. Study the more than 60 tax provisions that IRS has adjusted to keep deductions, tax brackets, and other items aligned with the cost of living. For those filing taxes in 2026 (for the 2025 tax year), these adjustments have increased by about 2.8%.
The Right Filing Status
Your filing status is used to determine your correct tax rate, standard deduction, and certain credits. Whether or not you are married, are the head of household, or have dependents are all factors in determining your filing status. The IRS offers a tool to help you choose the filing status that will result in the lowest amount of tax.
It pays to do a little research and know which status is best for your given situation. For instance, filing jointly as a married couple rather than separately comes with certain benefits, such as the most significant standard deduction, tax credits, and a higher income threshold. But if your spouse owes tax penalties, then that’s a situation where filing separately makes more sense.
How to File
When you can claim tax credits or otherwise have money owed to you, filing taxes can be a great thing. The IRS now offers Free File, a way to do your taxes online for free. People with potentially complex tax situations, such as multiple business ventures or multiple streams of income, may opt to work with a Certified Public Accountant (CPA). There are also many companies, like TurboTax that offer both free and fee-based services.
With Insureyouknow.org, you can get in the habit of storing this information throughout the year. That way, when it comes time to file, everything you need will be in one place.